主管:中国科学院
主办:中国优选法统筹法与经济数学研究会
中国科学院科技战略咨询研究院
主办:中国优选法统筹法与经济数学研究会
中国科学院科技战略咨询研究院
中国管理科学 ›› 2026, Vol. 34 ›› Issue (10): 1-13.doi: 10.16381/j.cnki.issn1003-207x.2022.0262
• •
姚海祥1,2, 张逸雪1, 李仲飞3( )
收稿日期:2022-02-14
修回日期:2022-09-13
出版日期:2026-10-25
发布日期:2026-10-09
通讯作者:
李仲飞
E-mail:lizf6@sustech.edu.cn
基金资助:
Haixiang Yao1,2, Yixue Zhang1, Zhongfei Li3()
Received:2022-02-14
Revised:2022-09-13
Online:2026-10-25
Published:2026-10-09
Contact:
Zhongfei Li
E-mail:lizf6@sustech.edu.cn
摘要:
Ban等[
中图分类号:
姚海祥,张逸雪,李仲飞. 基于绩效正则化法的均值-下偏矩投资组合选择[J]. 中国管理科学, 2026, 34(10): 1-13.
Haixiang Yao,Yixue Zhang,Zhongfei Li. Mean-lower Partial Moment Portfolio Selection Based on Performance-based Regularization Method[J]. Chinese Journal of Management Science, 2026, 34(10): 1-13.
图1
上证综指走势图"
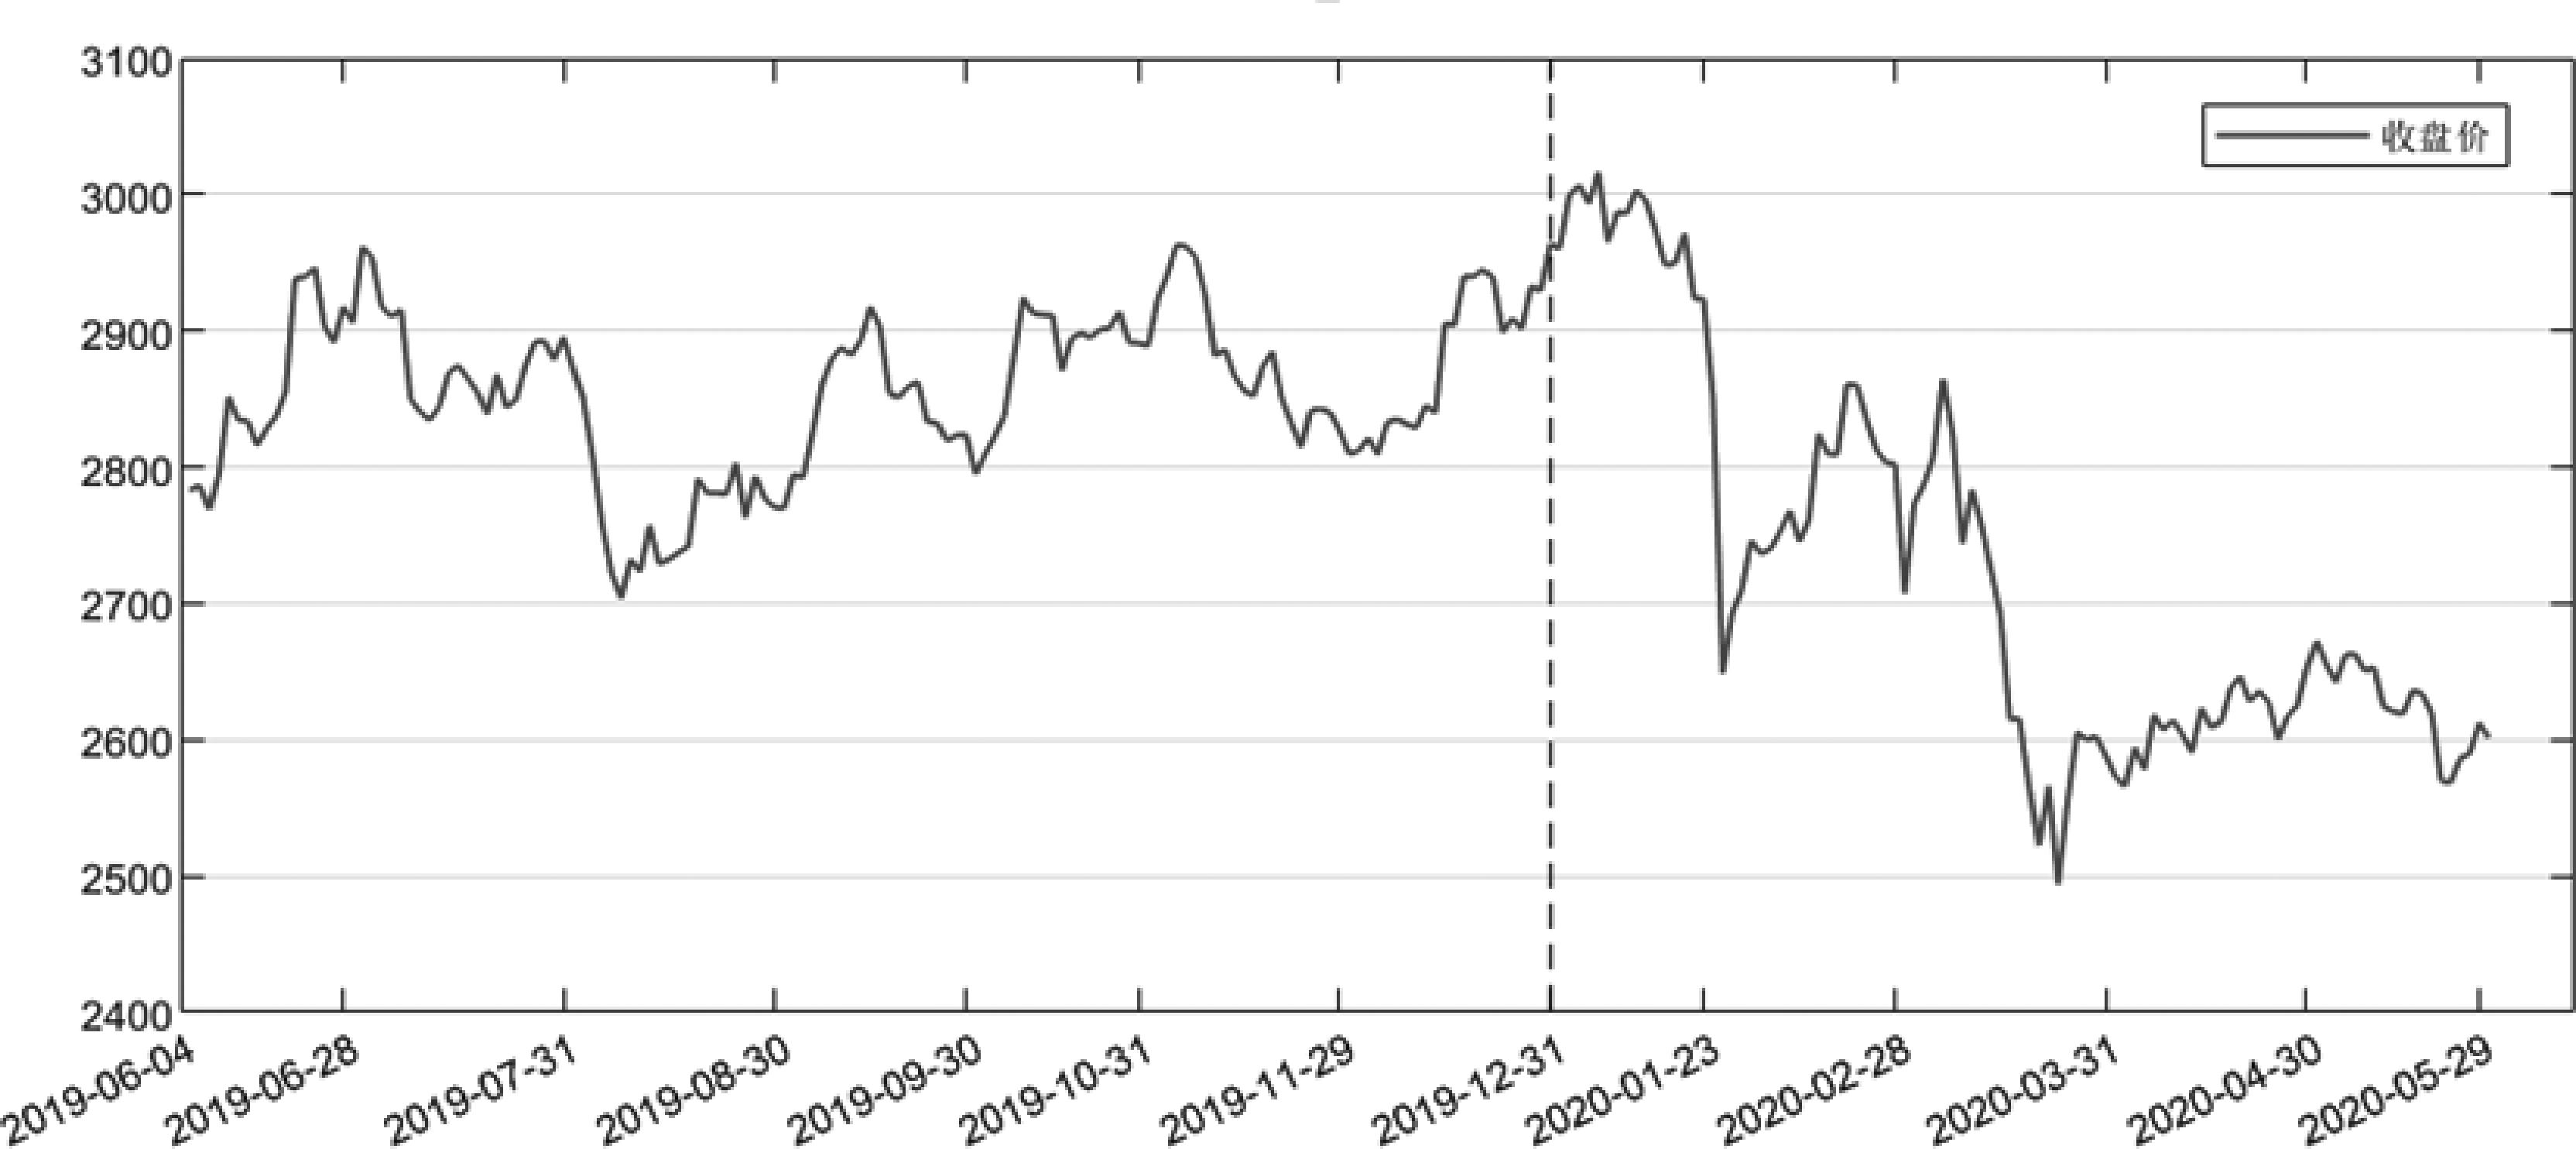

表1
投资组合数据集的描述性统计"
| 投资组合股票池 | 股票数量 | 均值的 最大值(%) | 均值的 最小值(%) | 标准差的 最大值(%) | 标准差的 最小值(%) | 收益率的 最大值(%) | 收益率的 最小值(%) |
|---|---|---|---|---|---|---|---|
| 沪深300指数中的30只成分股 | 30 | 3.39 | -7.68 | 3.65 | 0.78 | 10.02 | -10.05 |
| 上证50指数中的50只成分股 | 50 | 3.64 | -8.11 | 3.23 | 0.54 | 10.06 | -10.07 |
表2
沪深300指数中30只成分股关于投资绩效评价指标的实证结果"
下偏矩 阶数 | 期望收益率R | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
MV- PBR | SAA | PBR-m | PBR-z | PBR- both | MV- PBR | SAA | PBR-m | PBR-z | PBR- both | MV- PBR | SAA | PBR-m | PBR-z | PBR- both | ||
| 1 | 平均回报率 | -0.0004 | -0.0003 | -0.0003 | -0.0003 | 0.0004 | -0.0003 | -0.0002 | -0.0002 | -0.0002 | 0.0005 | -0.0003 | -0.0001 | -0.0001 | -0.0003 | 0.0006 |
| 夏普比率 | -0.0383 | -0.0292 | -0.0284 | -0.0287 | 0.0327 | -0.0342 | -0.0238 | -0.0216 | -0.0180 | 0.0405 | -0.0303 | -0.0164 | -0.0149 | -0.0255 | 0.0479 | |
| 索提诺比率 | -0.0436 | -0.0321 | -0.0310 | -0.0314 | 0.0521 | -0.0386 | -0.0252 | -0.0222 | -0.0174 | 0.0630 | -0.0336 | -0.0155 | -0.0136 | -0.0274 | 0.0737 | |
| Omega比率 | 0.9155 | 0.9363 | 0.9385 | 0.9390 | 1.1081 | 0.9253 | 0.9504 | 0.9561 | 0.9658 | 1.1305 | 0.9350 | 0.9693 | 0.9732 | 0.9466 | 1.1519 | |
| 换手率 | 0.1168 | 0.1476 | 0.1431 | 0.1539 | 0.1420 | 0.1262 | 0.1536 | 0.1514 | 0.1822 | 0.1485 | 0.1347 | 0.1567 | 0.1494 | 0.1732 | 0.1498 | |
| 累计收益率 | 0.9583 | 0.9668 | 0.9677 | 0.9673 | 1.0354 | 0.9616 | 0.9722 | 0.9747 | 0.9783 | 1.0448 | 0.9649 | 0.9800 | 0.9816 | 0.9690 | 1.0540 | |
| 2 | 平均回报率 | -0.0004 | -0.0004 | -0.0004 | -0.0003 | 0.0004 | -0.0003 | -0.0003 | -0.0003 | -0.0002 | 0.0005 | -0.0003 | -0.0003 | -0.0003 | -0.0002 | 0.0006 |
| 夏普比率 | -0.0383 | -0.0357 | -0.0371 | -0.0276 | 0.0338 | -0.0342 | -0.0313 | -0.0321 | -0.0238 | 0.0422 | -0.0303 | -0.0262 | -0.0268 | -0.0203 | 0.0500 | |
| 索提诺比率 | -0.0436 | -0.0403 | -0.0418 | -0.0298 | 0.0566 | -0.0386 | -0.0347 | -0.0359 | -0.0250 | 0.0689 | -0.0336 | -0.0283 | -0.0291 | -0.0206 | 0.0803 | |
| Omega比率 | 0.9155 | 0.9214 | 0.9182 | 0.9418 | 1.1067 | 0.9253 | 0.9323 | 0.9305 | 0.9510 | 1.1302 | 0.9350 | 0.9447 | 0.9434 | 0.9598 | 1.1524 | |
| 换手率 | 0.1168 | 0.1203 | 0.1785 | 0.1420 | 0.1201 | 0.1262 | 0.1294 | 0.1880 | 0.1468 | 0.1292 | 0.1347 | 0.1376 | 0.2105 | 0.1569 | 0.1374 | |
| 累计收益率 | 0.9583 | 0.9604 | 0.9599 | 0.9688 | 1.0352 | 0.9616 | 0.9642 | 0.9638 | 0.9721 | 1.0448 | 0.9649 | 0.9689 | 0.9684 | 0.9753 | 1.0542 | |
| 3 | 平均回报率 | -0.0004 | -0.0002 | -0.0003 | -0.0001 | 0.0006 | -0.0003 | -0.0001 | -0.0003 | -0.0001 | 0.0007 | -0.0003 | -0.0001 | -0.0003 | 0.0000 | 0.0008 |
| 夏普比率 | -0.0383 | -0.0191 | -0.0348 | -0.0169 | 0.0505 | -0.0342 | -0.0142 | -0.0309 | -0.0097 | 0.0586 | -0.0303 | -0.0097 | -0.0320 | -0.0043 | 0.0663 | |
| 索提诺比率 | -0.0436 | -0.0189 | -0.0390 | -0.0159 | 0.0835 | -0.0386 | -0.0126 | -0.0344 | -0.0066 | 0.0958 | -0.0336 | -0.0066 | -0.0359 | 0.0005 | 0.1076 | |
| Omega比率 | 0.9155 | 0.9630 | 0.9243 | 0.9689 | 1.1515 | 0.9253 | 0.9754 | 0.9336 | 0.9871 | 1.1743 | 0.9350 | 0.9871 | 0.9306 | 1.0009 | 1.1966 | |
| 换手率 | 0.1168 | 0.1183 | 0.2192 | 0.1323 | 0.1174 | 0.1262 | 0.1281 | 0.2394 | 0.1384 | 0.1285 | 0.1347 | 0.1364 | 0.2172 | 0.1458 | 0.1364 | |
| 累计收益率 | 0.9583 | 0.9777 | 0.9624 | 0.9801 | 1.0528 | 0.9616 | 0.9825 | 0.9652 | 0.9875 | 1.0627 | 0.9649 | 0.9872 | 0.9626 | 0.9933 | 1.0727 | |
| 4 | 平均回报率 | -0.0004 | 0.0000 | -0.0004 | 0.0000 | 0.0007 | -0.0003 | 0.0000 | -0.0003 | 0.0000 | 0.0008 | -0.0003 | 0.0001 | -0.0002 | 0.0001 | 0.0009 |
| 夏普比率 | -0.0383 | -0.0064 | -0.0369 | -0.0064 | 0.0607 | -0.0342 | -0.0030 | -0.0336 | -0.0030 | 0.0675 | -0.0303 | 0.0004 | -0.0247 | 0.0003 | 0.0772 | |
| 索提诺比率 | -0.0436 | -0.0021 | -0.0416 | -0.0021 | 0.1005 | -0.0386 | 0.0024 | -0.0378 | 0.0024 | 0.1110 | -0.0336 | 0.0068 | -0.0260 | 0.0067 | 0.1263 | |
| Omega比率 | 0.9155 | 0.9958 | 0.9192 | 0.9958 | 1.1804 | 0.9253 | 1.0047 | 0.9271 | 1.0047 | 1.2000 | 0.9350 | 1.0135 | 0.9491 | 1.0131 | 1.2281 | |
| 换手率 | 0.1168 | 0.1174 | 0.2349 | 0.1174 | 0.1191 | 0.1262 | 0.1266 | 0.2625 | 0.1267 | 0.1300 | 0.1347 | 0.1364 | 0.2716 | 0.1365 | 0.1384 | |
| 累计收益率 | 0.9583 | 0.9915 | 0.9599 | 0.9915 | 1.0643 | 0.9616 | 0.9951 | 0.9623 | 0.9951 | 1.0731 | 0.9649 | 0.9988 | 0.9709 | 0.9986 | 1.0858 | |
表3
上证50指数中50只成分股的关于投资绩效评价指标的实证结果"
下偏矩 阶数 | 期望收益率R | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
MV- PBR | SAA | PBR-m | PBR-z | PBR- both | MV- PBR | SAA | PBR-m | PBR-z | PBR- both | MV- PBR | SAA | PBR-m | PBR-z | PBR- both | ||
| 1 | 平均回报率 | -0.0008 | -0.0009 | -0.0010 | -0.0007 | -0.0005 | -0.0008 | -0.0009 | -0.0010 | -0.0008 | -0.0005 | -0.0008 | -0.0009 | -0.0009 | -0.0009 | -0.0004 |
| 夏普比率 | -0.0954 | -0.1006 | -0.1028 | -0.0830 | -0.0592 | -0.0947 | -0.1019 | -0.1035 | -0.0917 | -0.0545 | -0.0939 | -0.0994 | -0.1006 | -0.0960 | -0.0530 | |
| 索提诺比率 | -0.1076 | -0.0097 | -0.0098 | -0.0094 | -0.0092 | -0.1067 | -0.0098 | -0.0098 | -0.0094 | -0.0092 | -0.1059 | -0.0098 | -0.0098 | -0.0094 | -0.0092 | |
| Omega比率 | 0.7716 | 0.7573 | 0.7517 | 0.7971 | 0.8509 | 0.7739 | 0.7555 | 0.7514 | 0.7781 | 0.8645 | 0.7763 | 0.7618 | 0.7586 | 0.7716 | 0.8693 | |
| 换手率 | 0.1419 | 0.1910 | 0.1903 | 0.3696 | 0.1827 | 0.1451 | 0.1961 | 0.1920 | 0.3748 | 0.1884 | 0.1482 | 0.1987 | 0.1997 | 0.3423 | 0.1890 | |
| 累计收益率 | 0.9177 | 0.9092 | 0.9068 | 0.9262 | 0.9486 | 0.9180 | 0.9077 | 0.9062 | 0.9176 | 0.9525 | 0.9184 | 0.9097 | 0.9085 | 0.9131 | 0.9534 | |
| 2 | 平均回报率 | -0.0008 | -0.0009 | -0.0009 | -0.0006 | -0.0003 | -0.0008 | -0.0009 | -0.0008 | -0.0007 | -0.0004 | -0.0008 | -0.0009 | -0.0009 | -0.0007 | -0.0003 |
| 夏普比率 | -0.0954 | -0.0977 | -0.1005 | -0.0649 | -0.0437 | -0.0947 | -0.0987 | -0.0946 | -0.0773 | -0.0502 | -0.0939 | -0.0993 | -0.0969 | -0.0750 | -0.0428 | |
| 索提诺比率 | -0.1076 | -0.0094 | -0.0094 | -0.0092 | -0.0074 | -0.1067 | -0.0094 | -0.0092 | -0.0092 | -0.0078 | -0.1059 | -0.0094 | -0.0093 | -0.0092 | -0.0074 | |
| Omega比率 | 0.7716 | 0.7663 | 0.7590 | 0.8402 | 0.9016 | 0.7739 | 0.7647 | 0.7762 | 0.8114 | 0.8839 | 0.7763 | 0.7641 | 0.7708 | 0.8172 | 0.9042 | |
| 换手率 | 0.1419 | 0.1462 | 0.2134 | 0.2336 | 0.1954 | 0.1451 | 0.1510 | 0.2437 | 0.2189 | 0.1933 | 0.1482 | 0.1558 | 0.2350 | 0.2424 | 0.2161 | |
| 累计收益率 | 0.9177 | 0.9144 | 0.9132 | 0.9399 | 0.9672 | 0.9180 | 0.9133 | 0.9180 | 0.9288 | 0.9609 | 0.9184 | 0.9125 | 0.9158 | 0.9302 | 0.9675 | |
| 3 | 平均回报率 | -0.0008 | -0.0005 | -0.0008 | -0.0004 | -0.0004 | -0.0008 | -0.0005 | -0.0005 | -0.0004 | -0.0002 | -0.0008 | -0.0005 | -0.0008 | -0.0004 | -0.0002 |
| 夏普比率 | -0.0954 | -0.0568 | -0.0889 | -0.0417 | -0.0493 | -0.0947 | -0.0579 | -0.0637 | -0.0415 | -0.0341 | -0.0939 | -0.0584 | -0.0875 | -0.0435 | -0.0341 | |
| 索提诺比率 | -0.1076 | -0.0090 | -0.0091 | -0.0090 | -0.0075 | -0.1067 | -0.0090 | -0.0089 | -0.0090 | -0.0072 | -0.1059 | -0.0091 | -0.0091 | -0.0091 | -0.0074 | |
| Omega比率 | 0.7716 | 0.8623 | 0.7842 | 0.8980 | 0.8872 | 0.7739 | 0.8597 | 0.8467 | 0.8976 | 0.9263 | 0.7763 | 0.8587 | 0.7909 | 0.8929 | 0.9259 | |
| 换手率 | 0.1419 | 0.1388 | 0.4629 | 0.1928 | 0.1641 | 0.1451 | 0.1419 | 0.4285 | 0.1862 | 0.1615 | 0.1482 | 0.1429 | 0.4026 | 0.1821 | 0.1980 | |
| 累计收益率 | 0.9177 | 0.9468 | 0.9246 | 0.9578 | 0.9602 | 0.9180 | 0.9456 | 0.9439 | 0.9570 | 0.9728 | 0.9184 | 0.9449 | 0.9241 | 0.9554 | 0.9728 | |
| 4 | 平均回报率 | -0.0008 | -0.0004 | -0.0006 | -0.0004 | -0.0003 | -0.0008 | -0.0004 | -0.0006 | -0.0004 | -0.0003 | -0.0008 | -0.0004 | -0.0006 | -0.0004 | -0.0003 |
| 夏普比率 | -0.0954 | -0.0442 | -0.0680 | -0.0451 | -0.0390 | -0.0947 | -0.0438 | -0.0686 | -0.0443 | -0.0362 | -0.0939 | -0.0430 | -0.0628 | -0.0428 | -0.0372 | |
| 索提诺比率 | -0.1076 | -0.0089 | -0.0089 | -0.0089 | -0.0074 | -0.1067 | -0.0089 | -0.0090 | -0.0090 | -0.0074 | -0.1059 | -0.0089 | -0.0091 | -0.0089 | -0.0074 | |
| Omega比率 | 0.7716 | 0.8919 | 0.8332 | 0.8893 | 0.9117 | 0.7739 | 0.8931 | 0.8337 | 0.8918 | 0.9192 | 0.7763 | 0.8954 | 0.8500 | 0.8959 | 0.9166 | |
| 换手率 | 0.1419 | 0.1451 | 0.3491 | 0.1532 | 0.1479 | 0.1451 | 0.1482 | 0.3856 | 0.1630 | 0.1555 | 0.1482 | 0.1514 | 0.3662 | 0.1522 | 0.1555 | |
| 累计收益率 | 0.9177 | 0.9557 | 0.9388 | 0.9547 | 0.9670 | 0.9180 | 0.9559 | 0.9374 | 0.9553 | 0.9694 | 0.9184 | 0.9565 | 0.9416 | 0.9568 | 0.9684 | |
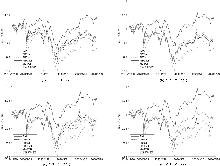
图2
沪深300指数中30只成分股的累计收益率曲线"

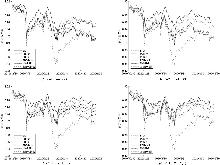
图3
上证50指数中50只成分股的累计收益率曲线"

| [1] | Ban G Y, El Karoui N, Lim A E B. Machine learning and portfolio optimization[J].Management Science, 2016, 64(3): 1136-1154. |
| [2] | Markowitz H. Portfolio selection[J]. The Journal of Finance, 1952, 7(1): 77-91. |
| [3] | Markowitz H M. Portfolio selection: Efficient diversification of investments[M].New York:John Wiley, 1959. |
| [4] | Fishburn P C. Mean-risk analysis with risk associated with below-target returns[J]. American Economic Review, 1977, 67(2): 116-126. |
| [5] | Bawa V S, Lindenberg E B. Capital market equilibrium in a mean-lower partial moment framework[J]. Journal of Financial Economics, 1977, 5(2): 189-200. |
| [6] | Mansini R, Speranza M G. Heuristic algorithms for the portfolio selection problem with minimum transaction lots[J]. European Journal of Operational Research, 1999, 114(2): 219-233. |
| [7] | Cai J, Jiao Z, Mao T. Worst-case values of target semi-variances with applications to robust portfolio selection[J]. European Journal of Operational Research, 2025, 327(3): 905-921. |
| [8] | Mei X, Wang Y, Zhu W. Bayesian nonparametric portfolio selection with rolling maximum drawdown control[J]. Quantitative Finance, 2023, 23(10): 1497-1510. |
| [9] | Yang X, Chen J, Liu W, et al. A multi-period fuzzy portfolio optimization model with investors’ loss aversion[J]. Soft Computing, 2023, 27(24): 18829-18842. |
| [10] | 黄金波, 李仲飞, 邹新月. 考虑下偏矩约束的增强指数模型[J]. 管理科学学报, 2019, 22(12): 56-69. |
| Huang J B, Li Z F, Zou X Y. Enhanced indexation model with lower partial moment constraint[J]. Journal of Management Sciences in China,2019,22(12): 56-69. | |
| [11] | Lassance N, Martín-Utrera A, Simaan M. The risk of expected utility under parameter uncertainty[J]. Management Science, 2024, 70(11): 7644-7663. |
| [12] | Shi F, Shu L, He F, et al. Improving minimum-variance portfolio through shrinkage of large covariance matrices[J].Economic Modelling, 2025, 144: 106981. |
| [13] | Tu J, Zhou G. Markowitz meets talmud: A combination of sophisticated and naive diversification strategies[J].Journal of Financial Economics,2011,99(1): 204-215. |
| [14] | Wu Z, Xie G, Ge Z, et al. Nonconvex multi-period mean-variance portfolio optimization[J]. Annals of Operations Research, 2024, 332(1): 617-644. |
| [15] | Zhao H, Kong L. Penalty method for the sparse portfolio optimization problem[J]. Journal of Industrial and Management Optimization, 2024, 20(9): 2864-2884. |
| [16] | Bian Z, Liao Y, O’Neill M, et al. Large-scale minimum variance portfolio allocation using double regularization[J]. Journal of Economic Dynamics and Control, 2020, 116: 103939. |
| [17] | 宋鹏, 刘程程, 胡永宏. 稳健高维协方差矩阵估计及其投资组合应用——基于中心正则化算法[J]. 统计研究, 2020, 37(7): 116-128. |
| Song P, Liu C C, Hu Y H. Robust high-dimensional covariance matrix estimation and the application in portfolio selection—Based on the central-regularized algorithm[J].Statistical Research,2020, 37(7): 116-128. | |
| [18] | Li Q, Zhang W. Sparse and risk diversification portfolio selection[J].Optimization Letters,2023,17(5): 1181-1200. |
| [19] | Wu Z, Sun K, Ge Z, et al. Sparse portfolio optimization via ℓ 1 over ℓ 2 regularization[J]. European Journal of Operational Research, 2024, 319(3): 820-833. |
| [20] | Kroll Y, Marchioni A, Ben-Horin M. Sortino(γ): A modified sortino ratio with adjusted threshold[J]. Journal of Accounting and Finance, 2023, 23(6): 6699. |
| [21] | Ghaemi Asl M, Rashidi M M, Tavakkoli H R, et al. Does Islamic investing modify portfolio performance? Time-varying optimization strategies for conventional and Shariah energy-ESG-utilities portfolio[J].The Quarterly Review of Economics and Finance, 2024, 94: 37-57. |
| [22] | DeMiguel V, Garlappi L, Nogales F J, et al. A generalized approach to portfolio optimization: Improving performance by constraining portfolio norms[J]. Management Science, 2009, 55(5): 798-812. |
| [23] | 陈宝林. 最优化理论与算法[M]. 2版. 北京: 清华大学出版社, 2005. |
| Chen B L. Optimization theory and algorithm[M]. 2nd ed. Beijing: Tsinghua University Press, 2005. | |
| [24] | Boyd S, Vandenberghe L. Convex optimization[M]. Cambridge, UK: Cambridge University Press, 2004. |
| [25] | Van der Vaart A W. Asymptotic statistics[M]. Cambridge, UK; New York, NY, USA: Cambridge University Press, 1998. |
| [26] | Yao H, Huang J, Li Y, et al. A general approach to smooth and convex portfolio optimization using lower partial moments[J]. Journal of Banking & Finance, 2021, 129: 106167. |
| [1] | 李舒霏, 程冲, 刘威汉. 基于几乎随机占优准则的中美理性投资者决策差异研究[J]. 中国管理科学, 2026, 34(7): 22-32. |
| [2] | 王良, 何俊杰, 黄国庆, 张金辉, 王潇涵. 基于前景理论与Bayes后验信念的风险投资项目最优投资时机研究[J]. 中国管理科学, 2026, 34(6): 22-35. |
| [3] | 徐涛, 陈庭强. 银行拆借偏好、网络结构演化与金融风险传染[J]. 中国管理科学, 2026, 34(6): 1-12. |
| [4] | 江雨燕, 黄体臣, 甘如美江, 王付宇. 基于KANsLTformer的黄金期货价格预测研究[J]. 中国管理科学, 2026, 34(5): 11-20. |
| [5] | 朱鹏飞, 卢团团, 魏宇, 林莎. 基于多小波降噪—分形标幅双集成法的股指期货套期保值比率估计研究[J]. 中国管理科学, 2026, 34(5): 21-34. |
| [6] | 吴鑫育, 尹学宝, 谢海滨, 马超群. 基于成分Realized EGARCH模型的期权定价研究[J]. 中国管理科学, 2026, 34(4): 22-33. |
| [7] | 张晗, 赵骅, 李志国, 蒋莉. 碳排放区域转移视角下政府规制与企业投资[J]. 中国管理科学, 2026, 34(4): 330-342. |
| [8] | 王远平, 杨金强, 孟祥煜. 时间偏好不一致性下的消费和投资选择——基于投资业绩稳定的视角[J]. 中国管理科学, 2026, 34(4): 1-12. |
| [9] | 俞乃畅, 程康, 李心丹, 杨学伟. 权证实现了股权分置改革对价支付功能吗?[J]. 中国管理科学, 2026, 34(3): 1-14. |
| [10] | 武瑶瑶, 邹镇涛. 模型不确定性下的企业最优资本结构[J]. 中国管理科学, 2026, 34(3): 51-56. |
| [11] | 张永, 黄清梅, 郑萧腾, 王福鼎, 杨兴雨. 考虑投资者关注度的反转型在线投资组合策略[J]. 中国管理科学, 2026, 34(2): 56-66. |
| [12] | 吴鑫育, 朱志田, 马超群. 经济政策不确定性与中国股市波动率——基于已实现SV-MIDAS模型的实证研究[J]. 中国管理科学, 2026, 34(1): 28-40. |
| [13] | 陈镇喜, 李京翰, 张维. 股价同步性——信息与噪声的统一框架[J]. 中国管理科学, 2026, 34(1): 41-59. |
| [14] | 马勇, 陈犁, 陈炜. 货币政策公告前的股价漂移:形成机理与影响因素[J]. 中国管理科学, 2026, 34(1): 60-71. |
| [15] | 李志楠, 雷静悦, 沈沛龙. 信息溢出对银企担保网络流动性风险传染的影响研究[J]. 中国管理科学, 2025, 33(12): 26-40. |
| 阅读次数 | ||||||
|
全文 |
|
|||||
|
摘要 |
|
|||||
|
||
