主管:中国科学院
主办:中国优选法统筹法与经济数学研究会
中国科学院科技战略咨询研究院
主办:中国优选法统筹法与经济数学研究会
中国科学院科技战略咨询研究院
Chinese Journal of Management Science ›› 2026, Vol. 34 ›› Issue (11): 23-32.doi: 10.16381/j.cnki.issn1003-207x.2023.2004
Previous Articles Next Articles
Xiaohong Chen1,2( ), Xuhang Wang1
Received:2023-11-29
Revised:2024-04-03
Online:2026-11-25
Published:2026-11-10
Contact:
Xiaohong Chen
E-mail:c88877803@163.com
CLC Number:
Xiaohong Chen,Xuhang Wang. Stock Market Investors' Effective Sentiment Mining Based on LSTM Neural Network[J]. Chinese Journal of Management Science, 2026, 34(11): 23-32.
"

"
| 股票代码 | 发布日期 | 贴文内容(加粗部分为识别情感词) |
|---|---|---|
| 601615 | 2020-06-12 | 凡是有减持计划的股票都是高风险的股票,被套的只有持股待涨,没有股票就不要买入了 |
| 600884 | 2021-08-23 | 明天板块大跌。就跌停不相信看!今天人气换手量都好假!很熟悉的套路。赶紧逃别来接盘 |
| 300724 | 2021-12-03 | 国家定调,重点支持太阳能光伏,氢能源等绿色环保企业!星期一起飞 |
| 002074 | 2021-12-12 | 加仓买进。涨停板来一个,涨停板不见不散 |
| 300014 | 2021-04-08 | 今天涨得还不错,上午找准了机会少量加了点,下午会涨 |
"
| 变量 | 均值 | 标准差 | 最小值 | 最大值 |
|---|---|---|---|---|
| 正向贴文数 | 31.739 | 51.248 | 0 | 1560 |
| 中性贴文数 | 34.604 | 57.488 | 0 | 1974 |
| 负向贴文数 | 28.839 | 52.148 | 0 | 1789 |
| 总贴文数 | 95.182 | 157.448 | 1 | 5323 |
| 评论数 | 190.739 | 439.604 | 0 | 17545 |
| 阅读量 | 79678.912 | 159945.711 | 11 | 4360775 |
| 情绪指数 | 0.148 | 0.618 | -2.708 | 3.219 |
"
| 特征变量 | 变量符号 | 含义 |
|---|---|---|
| 基本特征 | 第 | |
| 第 | ||
| 第 | ||
| 第 | ||
| 情绪特征 | 第 | |
| 第 |
"
"
| 变量 | 全时点 (obs=21177) | 异常时点 (obs=3867) | 非异常时点 (obs=17130) | ||||||
|---|---|---|---|---|---|---|---|---|---|
| 情绪指数 | 相对误差 | 收益率 | 情绪指数 | 相对误差 | 收益率 | 情绪指数 | 相对误差 | 收益率 | |
| 情绪指数 | 1 | 1 | 1 | ||||||
| 相对误差 | 0.110 | 1 | 0.162 | 1 | 0.116 | 1 | |||
| 收益率 | 0.359 | 0.196 | 1 | 0.452 | 0.252 | 1 | 0.332 | 0.189 | 1 |
"
| 变量 | 全时点 (obs=578) | 异常时点 (obs=155) | 非异常时点 (obs=423) | ||||||
|---|---|---|---|---|---|---|---|---|---|
| 情绪指数 | 相对误差 | 收益率 | 情绪指数 | 相对误差 | 收益率 | 情绪指数 | 相对误差 | 收益率 | |
| 情绪指数 | 1 | 1 | 1 | ||||||
| 相对误差 | 0.339 | 1 | 0.384 | 1 | 0.209 | 1 | |||
| 收益率 | 0.446 | 0.371 | 1 | 0.593 | 0.380 | 1 | 0.279 | 0.176 | 1 |
"
"
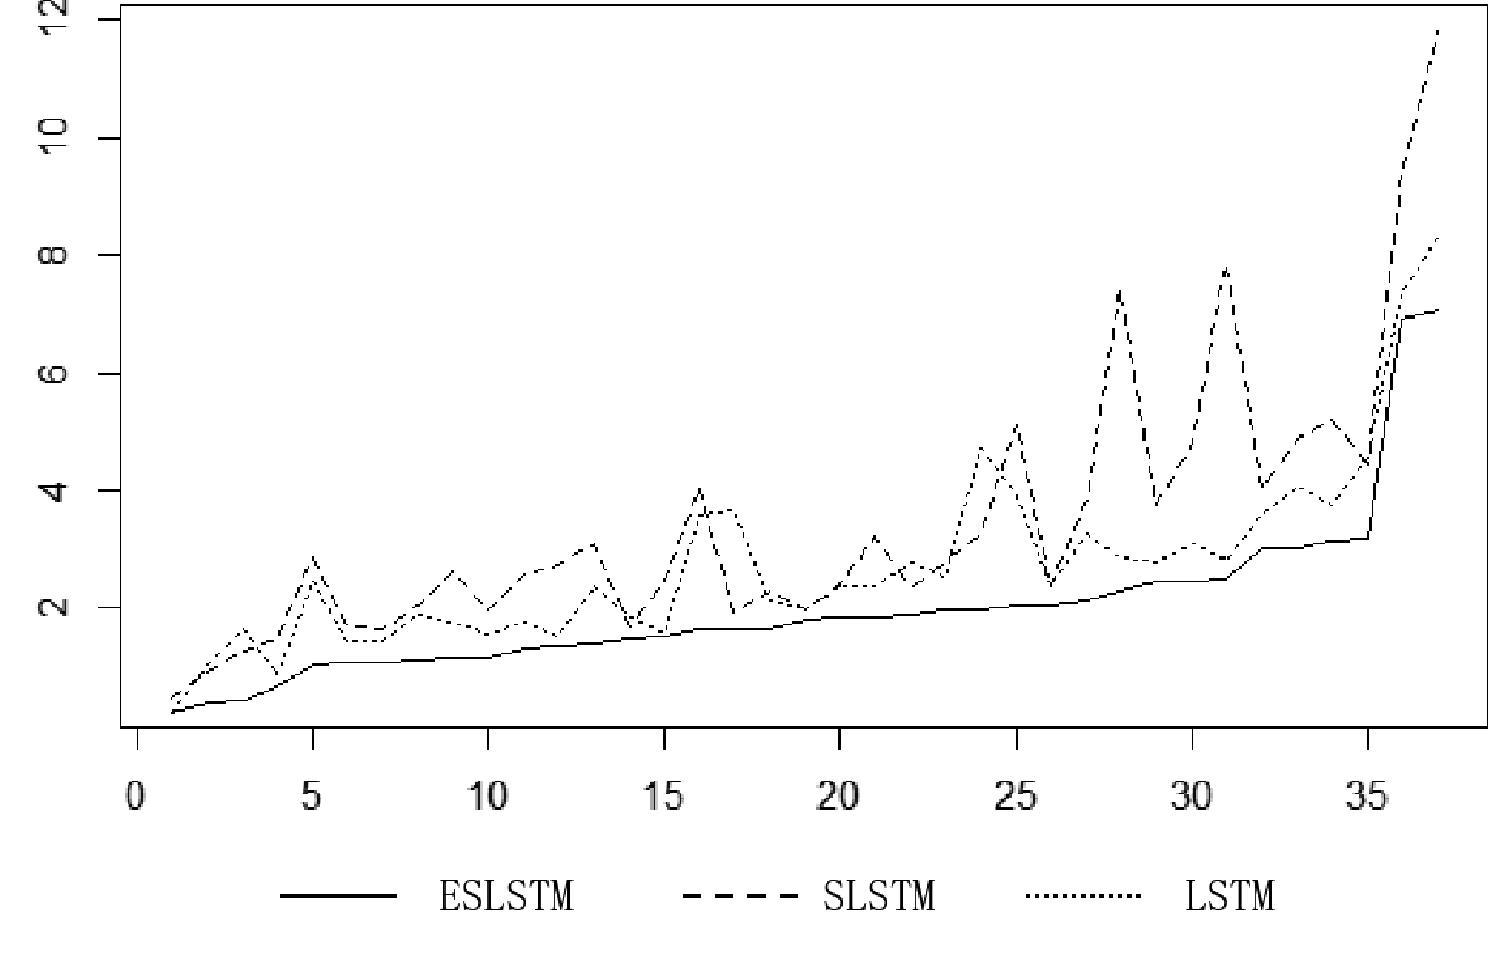
| 指标 | LSTM | S-LSTM | ES-LSTM |
|---|---|---|---|
| MSE | 50.485 | 59.902 | 37.746 |
| MAE | 5.907 | 5.722 | 5.119 |
| Mape | 2.371 | 2.392 | 2.062 |
"
| [1] | 张峥, 徐信忠. 行为金融学研究综述[J]. 管理世界, 2006, 22(9): 155-167. |
| Zhang Z, Xu X Z. A review of behavioral finance research[J].Management World,2006,22(9): 155-167. | |
| [2] | Malkiel B G, Fama E F. Efficient capital markets: A review of theory and empirical work[J]. The Journal of Finance, 1970, 25(2): 383-417. |
| [3] | Shleifer A. Inefficient markets: An introduction to behavioral finance[M].Oxford: Oxford University Press, 2000. |
| [4] | 王美今, 孙建军. 中国股市收益、收益波动与投资者情绪[J]. 经济研究, 2004, 39(10): 75-83. |
| Wang M J, Sun J J. Stock market returns, volatility and the role of investor sentiment in China[J]. Economic Research Journal, 2004, 39(10): 75-83. | |
| [5] | 文凤华, 肖金利, 黄创霞, 等. 投资者情绪特征对股票价格行为的影响研究[J]. 管理科学学报, 2014, 17(3): 60-69. |
| Wen F H, Xiao J L, Huang C X, et al. The effects of characteristics of investor sentiment on stock price behaviors[J]. Journal of Management Sciences in China, 2014, 17(3): 60-69. | |
| [6] | 罗衎, 王春峰, 房振明. 社会互动, 投资者情绪传染与资产泡沫——基于股票论坛发帖的实证研究[J]. 运筹与管理, 2018, 27(2): 124-132. |
| Luo K, Wang C F, Fang Z M. Social interaction, investor sentiment contagion and asset bubbles: An empirical study based on the stock forum discussion[J]. Operations Research and Management Science, 2018, 27(2): 124-132. | |
| [7] | 潘胜文, 吴川东. 涨幅限制、投资者情绪与IPO抑价[J]. 金融监管研究, 2020(8): 84-101. |
| Pan S W, Wu C D. Price limits, investor sentiments and IPO underpricing [J]. Financial Regulation Research, 2020(8): 84-101. | |
| [8] | De Long J B, Shleifer A, Summers L H, et al. Noise trader risk in financial markets[J]. Journal of Political Economy, 1990, 98(4): 703-738. |
| [9] | Antweiler W, Frank M Z. Is all that talk just noise? The information content of Internet stock message boards[J]. The Journal of Finance, 2004, 59(3): 1259-1294. |
| [10] | Bollen J, Mao H, Zeng X. Twitter mood predicts the stock market[J]. Journal of Computational Science, 2011, 2(1): 1-8. |
| [11] | 陈晓红, 彭宛露, 田美玉. 基于投资者情绪的股票价格及成交量预测研究[J]. 系统科学与数学, 2016, 36(12): 2294-2306. |
| Chen X H, Peng W L, Tian M Y. Stock market prediction based on investor sentiment[J]. Journal of Systems Science and Mathematical Sciences, 2016, 36(12): 2294-2306. | |
| [12] | 段江娇, 刘红忠, 曾剑平. 中国股票网络论坛的信息含量分析[J]. 金融研究, 2017(10): 178-192. |
| Duan J J, Liu H Z, Zeng J P. Analysis on the information content of China’s Internet stock message boards[J]. Journal of Financial Research, 2017(10): 178-192. | |
| [13] | 尹海员, 寇文娟. 基于朴素贝叶斯法的投资者情绪度量及其对股票特质风险的影响[J]. 中国管理科学, 2024, 32(4): 38-47. |
| Yin H Y, Kou W J. Investor sentiment based on naive Bayes method and its impact on stock idiosyncratic risk[J]. Chinese Journal of Management Science, 2024, 32(4): 38-47. | |
| [14] | Xing F Z, Cambria E, Zhang Y. Sentiment-aware volatility forecasting[J]. Knowledge-Based Systems, 2019, 176: 68-76. |
| [15] | 王娜, 贺毅岳, 刘磊. 股市投资者情绪指数构建及其有效性研究——基于东方财富股吧帖文的情感分析[J]. 价格理论与实践, 2022(11): 146-151. |
| Wang N, He Y Y, Liu L. Research on the construction and effectiveness of investor sentiment index: Based on emotional analysis oriental wealth stock bar posts[J]. Price (Theory & Practice), 2022(11): 146-151. | |
| [16] | 于孝建, 刘国鹏, 刘建林, 等. 基于LSTM网络和文本情感分析的股票指数预测[J]. 中国管理科学, 2024, 32(8): 25-35. |
| Yu X J, Liu G P, Liu J L, et al. Stock index prediction based on LSTM network and text sentiment analysis[J]. Chinese Journal of Management Science, 2024, 32(8): 25-35. | |
| [17] | Baker M, Wurgler J. Investor sentiment and the cross-section of stock returns[J]. The Journal of Finance, 2006, 61(4): 1645-1680. |
| [18] | 蒋玉梅, 王明照. 投资者情绪与股票收益: 总体效应与横截面效应的实证研究[J]. 南开管理评论, 2010, 13(3): 150-160. |
| Jiang Y M, Wang M Z. Investor sentiment and stock returns: An empirical study on aggregate effects and cross-section effects[J]. Nankai Business Review, 2010, 13(3): 150-160. | |
| [19] | Loughran T I M, McDonald B. When is a liability not a liability? Textual analysis, dictionaries, and 10-ks[J]. The Journal of Finance, 2011, 66(1): 35-65. |
| [20] | 姚加权, 冯绪, 王赞钧, 等. 语调、情绪及市场影响: 基于金融情绪词典[J]. 管理科学学报, 2021, 24(5): 26-46. |
| Yao J Q, Feng X, Wang Z J, et al. Tone, sentiment and market impacts: The construction of Chinese sentiment dictionary in finance[J]. Journal of Management Sciences in China, 2021, 24(5): 26-46. | |
| [21] | 欧阳红兵, 黄亢, 闫洪举. 基于LSTM神经网络的金融时间序列预测[J]. 中国管理科学, 2020, 28(4): 27-35. |
| Ouyang H B, Huang K, Yan H J. Prediction of financial time series based on LSTM neural network[J]. Chinese Journal of Management Science, 2020, 28(4): 27-35. | |
| [22] | Ma Q. Comparison of ARIMA, ANN and LSTM for stock price prediction[J]. E3S Web of Conferences, 2020, 218: 01026. |
| [23] | J S. Gradient flow in recurrent nets: the difficulty of learning long-term dependencies[M].New York:Wiley-IEEE Press, 2001. |
| [24] | Sutskever I, Vinyals, O, LE, Q V. Sequence to sequence learning with neural networks[C]//Proceedings of the 28th International Conference on Neural Information Processing Systems,Montreal,Quebec,Canada,December 8-13,Curran Associates,2014:3104-3112. |
| [25] | Guyon I, Elisseeff A. An introduction to variable and feature selection[J]. Journal of Machine Learning Research, 2003, 3: 1157-1182. |
| [26] | 部慧, 解峥, 李佳鸿, 等. 基于股评的投资者情绪对股票市场的影响[J].管理科学学报,2018, 21(4): 86-101. |
| Bu H, Xie Z, Li J H, et al. Investor sentiment extracted from Internet stock message boards and its effect on Chinese stock market[J]. Journal of Management Sciences in China, 2018, 21(4): 86-101. |
| [1] | Guowen Li, Yuhao Gong, Jingyu Li, Shuai Wang. Test for Anomalous Distribution of Information Disclosure: A New Strategy for Financial Fraud Detection [J]. Chinese Journal of Management Science, 2026, 34(2): 67-78. |
| [2] | Yunfeng Chen, Xue Yu, Jicheng Liu, Xuying Ma, Xirui Zhu. Research on Electric Coal Inventory Risk Assessment Based on TSO-LS-SVM Model [J]. Chinese Journal of Management Science, 2026, 34(2): 164-175. |
| [3] | Zhongyi Hu, Diancheng Shui, Jiang Wu. Measurement and Evolution of Digitization Level of Chinese Listed Companies: Empirical Evidence from Annual Report Text [J]. Chinese Journal of Management Science, 2025, 33(4): 36-49. |
| [4] | Gang Li, Chaochao Qiu, Zhipeng Zhang, Simeng Qin, Xingnan Xue. Research on Predicting Corporate Fraud of Listed Companies Based on Multi-Source Text Data and Feature-Augmented Tree Models [J]. Chinese Journal of Management Science, 2025, 33(11): 29-40. |
| [5] | Wanhai You, Senjie Chen, Jianyong Chen, Yinghua Ren. The Impact of “More Words Than Deeds” on Environmental Responsibility on Stock Price Crash Risk: The Mediation Effect of Investor Sentiment [J]. Chinese Journal of Management Science, 2025, 33(10): 12-23. |
| [6] | Xiaojian Yu,Guopeng Liu,Jianlin Liu,Weilin Xiao. Stock Index Prediction Based on LSTM Network and Text Sentiment Analysis [J]. Chinese Journal of Management Science, 2024, 32(8): 25-35. |
| [7] | WANG Jing. Study on the Formation Mechanism of Synergistic Drive to Upgrade the Modernization Level of Industrial Chain and Supply Chain: Based on BP-SVM Joint Optimization Model [J]. Chinese Journal of Management Science, 2023, 31(6): 196-206. |
| [8] | DONG Bing-jie, CHI Guo-tai. Study on Default Prediction Based on Sentiment Data [J]. Chinese Journal of Management Science, 2023, 31(4): 111-120. |
| [9] | HUANG Xing, YUN Ming, WANG Shao-yu. The Survival Amount Model Based on Mexican Wavelet Nuclear-SVM in Earthquake Disaster [J]. Chinese Journal of Management Science, 2016, 24(9): 140-146. |
| [10] | ZHANG Gui-sheng, ZHANG Xin-dong. A SVM-GARCH Model for Stock Price Forecasting Based on Neighborhood Mutual Information [J]. Chinese Journal of Management Science, 2016, 24(9): 11-20. |
| [11] | WANG Shu-ping, ZHU Yan-yun. Forecasting of Wheatprice Based on Multi-scale Analysis [J]. Chinese Journal of Management Science, 2016, 24(5): 85-91. |
| [12] | ZHANG Liang, ZHANG Ling-ling, CHEN Yi-bing, TENG Wei-li. Based on Information Fusion Technique with Data Mining in the Application of Finance Early-Warning [J]. Chinese Journal of Management Science, 2015, 23(10): 170-176. |
| [13] | WANG Shu-ping, HU Ai-mei, WU Zhen-xin. Forecasting of Copper Price based on Multi-scale Combined Model [J]. Chinese Journal of Management Science, 2014, 22(8): 21-28. |
| [14] | SAI Ying, ZHANG Feng-ting, ZHANG Tao. Research of Chinese Stock Index Futures Regression Prediction Based on Support Vector Machines [J]. Chinese Journal of Management Science, 2013, 21(3): 35-39. |
| [15] | JI Yan-guang, XU Qi-hua, HAN Zhi-jun. The Metric of Process Quality of R&D Project Based on SVM [J]. Chinese Journal of Management Science, 2004, (6): 62-67. |
| Viewed | ||||||
|
Full text |
|
|||||
|
Abstract |
|
|||||
|
||
