主管:中国科学院
主办:中国优选法统筹法与经济数学研究会
中国科学院科技战略咨询研究院
主办:中国优选法统筹法与经济数学研究会
中国科学院科技战略咨询研究院
Chinese Journal of Management Science ›› 2026, Vol. 34 ›› Issue (11): 14-22.doi: 10.16381/j.cnki.issn1003-207x.2022.2545
Previous Articles Next Articles
Xunfa Lu1, Kai Liu2, Hairong Cui1, Kin Keung Lai3( )
Received:2022-11-25
Revised:2023-02-10
Online:2026-11-25
Published:2026-11-10
Contact:
Kin Keung Lai
E-mail:mskklai@outlook.com
CLC Number:
Xunfa Lu,Kai Liu,Hairong Cui, et al. Study on the Causality Between International Crude Oil Futures Market and Chinese Stock Index Futures Market[J]. Chinese Journal of Management Science, 2026, 34(11): 14-22.
"
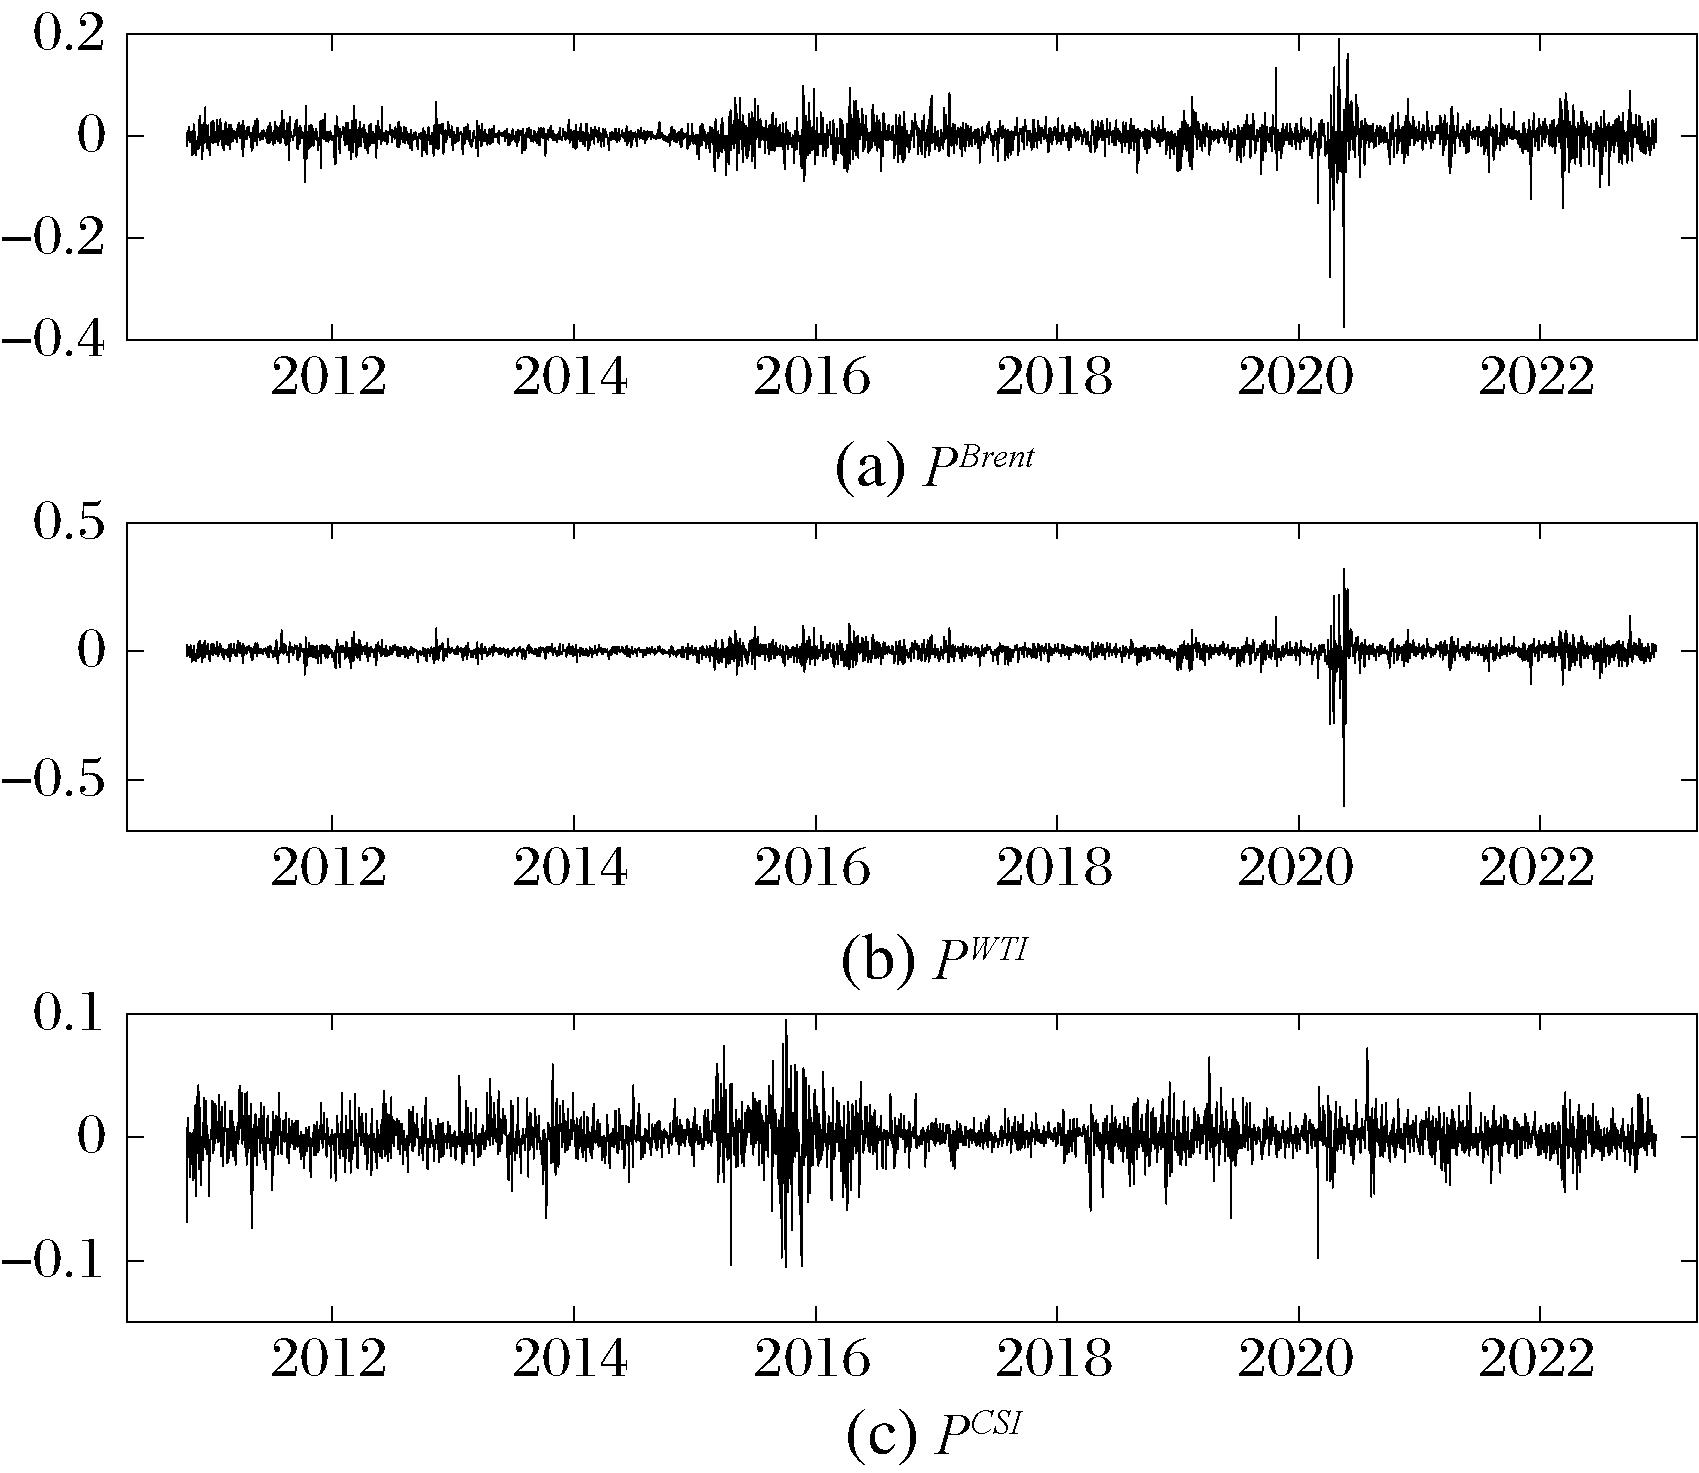
"

"
| 变量名 | |||
|---|---|---|---|
| 均值 | -5.75×10⁻⁶ | -1.58×10⁻⁵ | 3.70×10⁻⁵ |
| 标准差 | 0.024283 | 0.029626 | 0.015003 |
| 峰度 | 31.57330 | 77.02570 | 10.24314 |
| 偏度 | -1.541395 | -2.595647 | -0.445509 |
| 最大值 | 0.190774 | 0.319634 | 0.095263 |
| 最小值 | -0.373399 | -0.601676 | -0.105239 |
| ADF检验 | -55.88139*** | -27.97573*** | -40.44035*** |
"
| 因果关系方向 | 梁氏因果分析 |
|---|---|
| 0.0043* | |
| 0.0055** | |
| 0.0051** | |
| 0.0024 |
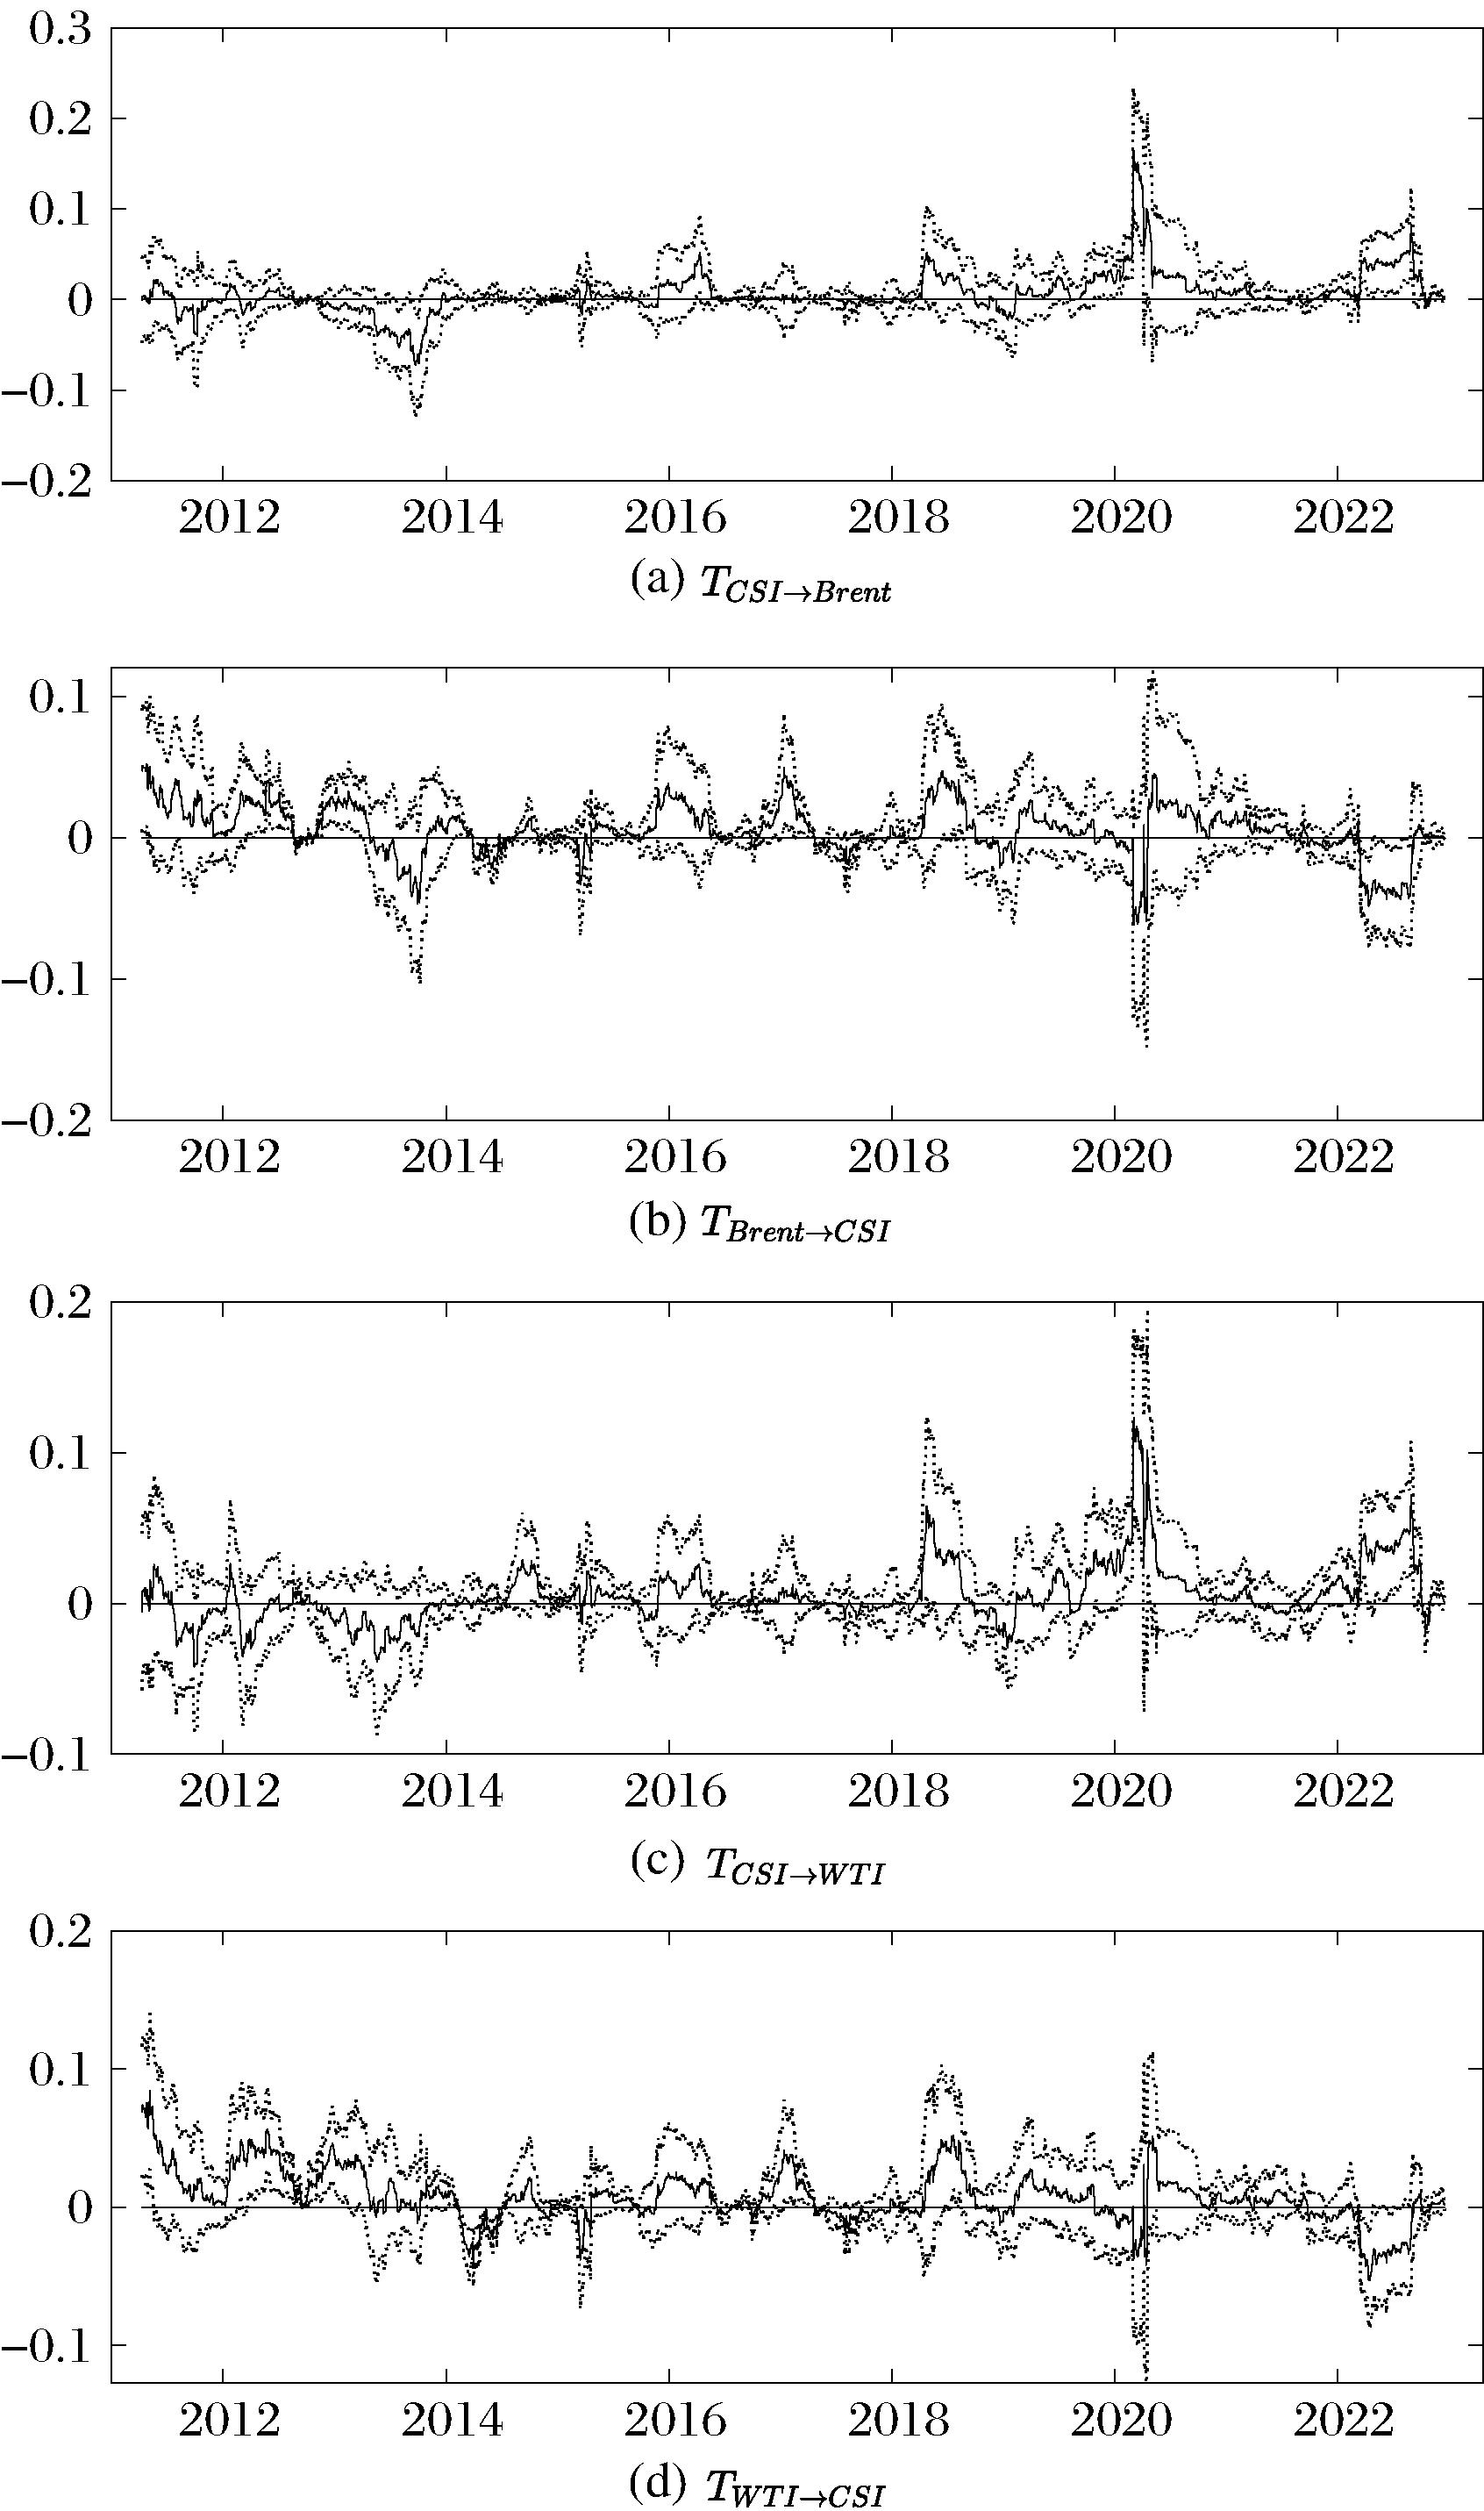
"
"
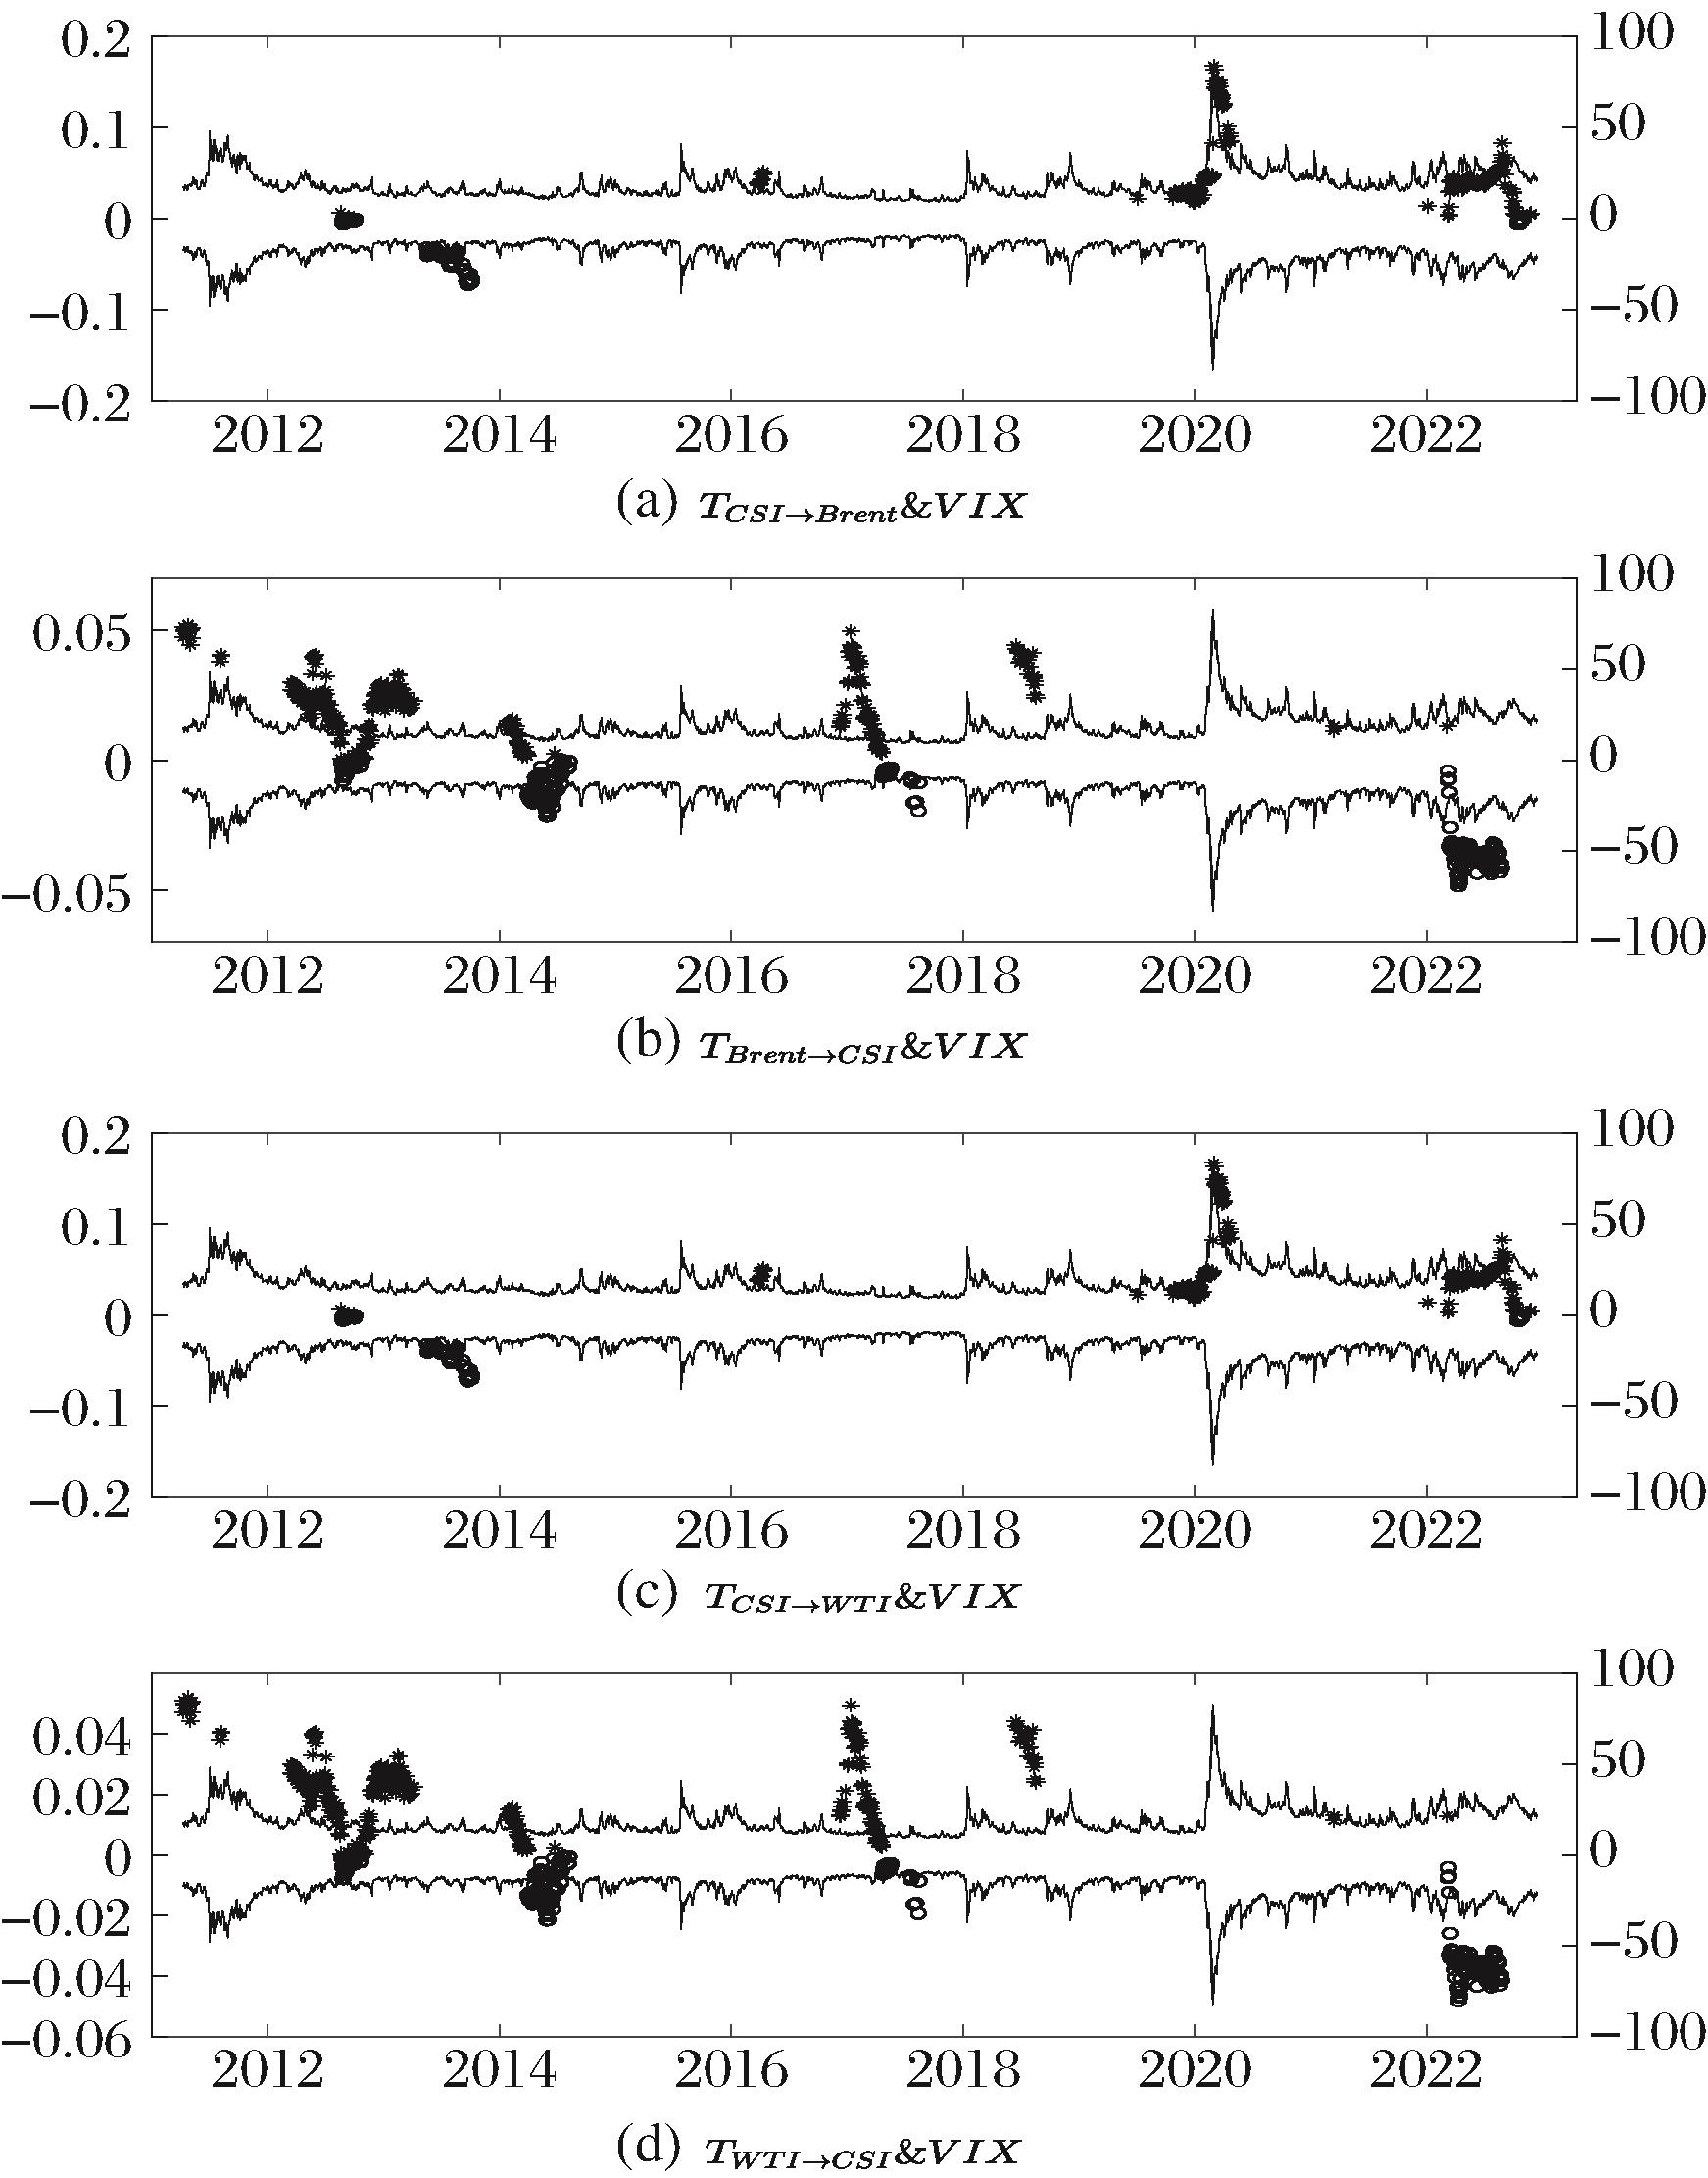
"

| [1] | 张维, 庞圆圆, 熊熊. 国际原油期货市场与中国股票市场联动关系探究[J].经济研究导刊,2018(10): 87-90. |
| Zhang W, Pang Y Y, Xiong X. The linkage between crude oil futures market and Chinese equity market[J]. Economig Rfsearch Cuide, 2018(10): 87-90. | |
| [2] | 刘映琳, 刘永辉, 鞠卓. 国际原油价格波动对中国商品期货的影响——基于多重相关性结构断点的分析[J]. 中国管理科学, 2019, 27(2): 31-40. |
| Liu Y L, Liu Y H, Ju Z. The impact of international crude oil price fluctuation on Chinese commodity futures: Based on the correlation structure breakpoint model[J]. Chinese Journal of Management Science, 2019, 27(2): 31-40. | |
| [3] | Lu X, He P, Zhang Z, et al. Extreme co-movements between decomposed oil price shocks and sustainable investments[J].Energy Economics, 2024, 134: 107580. |
| [4] | Wan M, Sun J, Sui C. Dynamic linkage and risk transmission mechanisms between crude oil and China-US stock markets: A multi-scale perspective[J]. Applied Economics, 2026, Online. |
| [5] | 程冬, 郑文平, 俞剑. 国际油价波动与中国制造业企业的成长表现[J]. 中央财经大学学报, 2019(6): 71-88. |
| Cheng D, Zheng W P, Yu J. Oil price fluctuations and the performance of China’s manufacturing firms[J]. Journal of Central University of Finance & Economics, 2019(6): 71-88. | |
| [6] | 肖继宏, 张靖宇, 张耀杰. 全球风险厌恶、国际金融市场和中国原油期货市场的时变溢出效应[J]. 系统管理学报, 2025, 34(2): 312-324. |
| Xiao J H, Zhang J Y, Zhang Y J. Time-varying spillover effects of global risk aversion, international financial markets, and the Chinese crude oil futures market[J]. Journal of Systems & Management, 2025, 34(2): 312-324. | |
| [7] | 鲁训法, 崔海蓉. 基于GARCH族混合模型的沪深300指数波动预测[J]. 阅江学刊, 2019, 11(3): 78-87+120. |
| Lu X F, Cui H R. Volatility forecast of Shanghai and Shenzhen 300 index based on GARCH hybrid model[J]. Yuejiang Academic Journal,2019, 11(3): 78-87+120. | |
| [8] | Gong X, Wen F, Pan B, et al. Analyzing the risk-return relationship in crude oil futures market using high-frequency data[J].Energy Procedia,2016, 104: 462-467. |
| [9] | Shao Y H, Yang Y H, Shao H L, et al. Time-varying lead–lag structure between the crude oil spot and futures markets[J]. Physica A: Statistical Mechanics and its Applications, 2019, 523: 723-733. |
| [10] | Berk I, Çam E. The shift in global crude oil market structure: A model-based analysis of the period 2013–2017[J]. Energy Policy, 2020, 142: 111497. |
| [11] | Zavadska M, Morales L, Coughlan J. Brent crude oil prices volatility during major crises[J]. Finance Research Letters, 2020, 32: 101078. |
| [12] | Wang J, Shao W, Kim J. Analysis of the impact of COVID-19 on the correlations between crude oil and agricultural futures[J]. Chaos, Solitons & Fractals, 2020, 136: 109896. |
| [13] | 陈粘, 林宇, 黄登仕, 等. Brent原油期货市场波动结构突变点预测[J]. 系统管理学报, 2019, 28(6): 1095-1105. |
| Chen Z, Lin Y, Huang D S, et al. Forecasting of structure breakthrough points in Brent crude oil futures market[J]. Journal of Systems & Management, 2019, 28(6): 1095-1105. | |
| [14] | 唐勇, 朱鹏飞. 沪深300股指期货牛熊周期的长记忆性、风险和有效性实证研究: 基于多重分形视角[J]. 管理评论, 2019, 31(8): 59-70. |
| Tang Y, Zhu P F. Research of long memory, risk and efficiency of bull and bear based on CSI300 index futures: From the perspective of multifractality[J]. Management Review, 2019, 31(8): 59-70. | |
| [15] | 单亮, 杨苗燕. 中国股指期货市场定价效率研究——基于自激励门限自回归模型[J]. 南方金融, 2019(9): 71-79. |
| Shan L, Yang M Y. The pricing efficiency of China’s stock index futures market: Based on SETAR model[J]. South China Finance, 2019(9): 71-79. | |
| [16] | 朱莉. 沪深300股指期现货市场信息溢出的因果检验——基于股指期货市场政策频繁调整期的数据[J]. 金融理论与实践, 2019(8): 71-76. |
| Zhu L. Causality test of information spillover in IF300 stock index futures-spot market: Data based on frequent adjustment period of stock index futures market policy[J]. Financial Theory and Practice, 2019(8): 71-76. | |
| [17] | Miao H, Ramchander S, Wang T, et al. Role of index futures on China’s stock markets: Evidence from price discovery and volatility spillover[J]. Pacific-Basin Finance Journal, 2017, 44: 13-26. |
| [18] | Hou Y, Li S. Volatility and skewness spillover between stock index and stock index futures markets during a crash period: New evidence from China[J]. International Review of Economics and Finance, 2020, 66: 166-188. |
| [19] | Wei Y, Qin S, Li X, et al. Oil price fluctuation, stock market and macroeconomic fundamentals: Evidence from China before and after the financial crisis[J]. Finance Research Letters, 2019, 30: 23-29. |
| [20] | Bouri E, Lien D, Roubaud D, et al. Directional predictability of implied volatility: From crude oil to developed and emerging stock markets[J]. Finance Research Letters, 2018, 27: 65-79. |
| [21] | Ahmed A D, Huo R. Volatility transmissions across international oil market, commodity futures and stock markets: Empirical evidence from China[J]. Energy Economics, 2021, 93: 104741. |
| [22] | 张年华, 黄佳耿, 曹啸, 等. 中国原油期货市场和金融市场的时变动态关系及风险溢出研究[J]. 计量经济学报, 2026,DOI: 10. 12012/CJoE2025-0552 . |
| Zhang N H, Hang J G, Cao X,et al. Time-varying dynamic relationship and risk spillover between China crude oil futures market and financial market[J]. China Journal of Econometrics, 2026,DOI: 10. 12012/CJoE2025-0552 . | |
| [23] | Hou Y, Li S, Wen F. Time-varying volatility spillover between Chinese fuel oil and stock index futures markets based on a DCC-GARCH model with a semi-nonparametric approach[J]. Energy Economics, 2019, 83: 119-143. |
| [24] | 李竹芸. 国际原油价格波动对我国股市的影响研究——基于不同行业的分析[J]. 金融经济, 2020(4): 54-66. |
| Li Z Y. Research on the impact of international crude oil price fluctuation on China’s stock market: Based on the analysis of different industries[J]. Finance Economy, 2020(4): 54-66. | |
| [25] | Sezen S, Cevik E I, Al-Eisa E A, et al. Investigating the connectedness between oil and stock markets in GCC countries: Evidence from rolling-window frequency domain causality[J]. Computational Economics, 2025, 66: 4869-4896. |
| [26] | Granger C W J. Investigating causal relations by econometric models and cross-spectral methods[J]. Econometrica, 1969, 37: 424-438. |
| [27] | Smirnov D A. Spurious causalities with transfer entropy[J]. Physical Review E, 2013, 87(4): 042917. |
| [28] | Bouezmarni T, Doukali M, Taamouti A. Testing granger non-causality in expectiles[J]. Econometric Reviews, 2024, 43(1): 30-51. |
| [29] | Schreiber T. Measuring information transfer[J]. Physical Review Letters, 2000, 85(2): 461-464. |
| [30] | Liang X. Unraveling the cause-effect relation between time series[J]. Physical Review E, 2014, 90(5): 052150. |
| [31] | Stips A, Macias D, Coughlan C, et al. On the causal structure between CO2 and global temperature[J]. Scientific Reports, 2016, 6: 21691. |
| [32] | Zhou F, Hagan D F T, Wang G, et al. Estimating time-dependent structures in a multivariate causality for land–atmosphere interactions[J]. Journal of Climate, 2024, 37(6): 1853-1876. |
| [33] | Lu X, Liu K, Liang X, et al. The break point-dependent causality between the cryptocurrency and emerging stock markets[J]. Economic Computation and Economic Cybernetics Studies and Research, 2020, 54: 203-216. |
| [34] | Lu X, Liu K, Liang X, et al. The dynamic causality in sporadic bursts between CO2 emission allowance prices and clean energy index[J]. Environmental Science and Pollution Research, 2022, 29(51): 77724-77736. |
| [35] | Hong Y. A test for volatility spillover with application to exchange rates[J]. Journal of Econometrics, 2001, 103(1-2): 183-224. |
| [36] | Liang X. Information flow and causality as rigorous notions ab initio[J]. Physical Review E, 2016, 94(5): 052201. |
| [37] | Hmamouche Y. NlinTS: An R package for causality detection in time series[J]. The R Journal, 2020, 12(1): 21-31. |
| [1] | Nianhua Zhang. Risk Spillover of Global Crude Oil Futures Market under Emergency Event [J]. Chinese Journal of Management Science, 2025, 33(4): 62-70. |
| [2] | Kun Yang, Yu Wei, Qianting Ma, Jianmin He, Wenhua Yu. The International Pricing Power of China's Crude Oil Futures: Comparative Analyses from the Perspective of Dynamic Information Spillover [J]. Chinese Journal of Management Science, 2024, 32(11): 13-24. |
| [3] | LIU Mu-han, XIONG Xiong,. Stock Index Futures Trading Policy, Investors’ Behavior and Stock Market Quality [J]. Chinese Journal of Management Science, 2023, 31(7): 126-139. |
| [4] | YANG Kun, WEI Yu, LI Shou-wei, HE Jian-min. Does Geopolitical Risk Drive China’s Crude Oil Futures Market? A Wavelet-based Nonparametric Causality-in-Quantiles Test [J]. Chinese Journal of Management Science, 2023, 31(2): 51-62. |
| [5] | ZHANG Da-yong, JI Qiang. Studies on the Dynamic Risk Spillovers for China's Crude Oil Futures [J]. Chinese Journal of Management Science, 2018, 26(11): 42-49. |
| [6] | JIAN Zhi-hong, ZENG Yu-feng, LIU Xi-teng. Study on CSI 300 Stock Index Futures Overnight Risk Based on CAViaR Model [J]. Chinese Journal of Management Science, 2016, 24(9): 1-10. |
| [7] | DAI Jun, ZHU Xin-ling. Hedging Effectiveness of the Hushen 300 Stock Index Futures Contracts [J]. Chinese Journal of Management Science, 2014, 22(4): 1-8. |
| [8] | TANG Yan-wei, CHEN Gang, LIU Xi-hua. Continuous Optimal Liquidation of the Single Hedged Stock under Arithmetic Brownian Movements without Drift [J]. Chinese Journal of Management Science, 2014, 22(2): 10-15. |
| [9] | QIAO Gao-xiu, LIU Qiang, ZHANG Mao-jun. The Impact of CSI 300 Index Futures on the Continuous Volatility and Jump Volatility of the Cash Market in China [J]. Chinese Journal of Management Science, 2014, 22(10): 9-18. |
| [10] | SAI Ying, ZHANG Feng-ting, ZHANG Tao. Research of Chinese Stock Index Futures Regression Prediction Based on Support Vector Machines [J]. Chinese Journal of Management Science, 2013, 21(3): 35-39. |
| [11] | ZHOU Ren-cai. The Stock Index Futures Hedging Strategy Based on the Risk Decomposition [J]. Chinese Journal of Management Science, 2013, (2): 17-23. |
| [12] | CHAI Shang-lei, GUO Chong-hui, SU Mu-ya. Volatility Spillover from International Stock Index Futures and Spot Markets to Chinese Stock Market Based on ICA Model [J]. Chinese Journal of Management Science, 2011, 19(3): 11-18. |
| Viewed | ||||||
|
Full text |
|
|||||
|
Abstract |
|
|||||
|
||
