主管:中国科学院
主办:中国优选法统筹法与经济数学研究会
中国科学院科技战略咨询研究院
主办:中国优选法统筹法与经济数学研究会
中国科学院科技战略咨询研究院
Chinese Journal of Management Science ›› 2026, Vol. 34 ›› Issue (10): 28-38.doi: 10.16381/j.cnki.issn1003-207x.2022.1040
Previous Articles Next Articles
Dabin Zhang1,2,3, Zhimei Zeng1, Liwen Ling1,2( ), Ruibin Lin1
Received:2022-05-12
Revised:2022-12-15
Online:2026-10-25
Published:2026-10-09
Contact:
Liwen Ling
E-mail:linglw@scau.edu.cn
CLC Number:
Dabin Zhang,Zhimei Zeng,Liwen Ling, et al. Prediction of Corn Futures Price Based on Multi-feature Deep Neural Network Model[J]. Chinese Journal of Management Science, 2026, 34(10): 28-38.
"
"
"
"
"

"
| 日期 | 当日新闻标题 |
|---|---|
| 2012-12-27 | 山东烟台购销渐显活跃玉米价格暂稳 |
| 黑龙江省双城区玉米价格暂稳 | |
| 2012-12-28 | 饲用需求提振玉米有望突破上行 |
| CBOT玉米期货连跌第二日,受累于美国财政忧虑 | |
| … | … |
| 2021-07-29 | “烟花”将进入山东京津冀等地风雨强 |
| 上涨情绪进一步上升玉米市场迎来反弹行情 | |
| 2021-07-30 | “暴雨”“烟花”叠加市场炒作天气缺“火候” |
| 缺乏需求提振玉米淀粉价格或回归震荡调整走势 |
"
"
| 参数 | BiLSTM | textCNN |
|---|---|---|
| 单层LSTM神经元个数 | 5 | — |
| 卷积核个数 | — | 100 |
| 卷积核大小 | — | 3,4,5 |
| Dropout | 0.25 | 0.5 |
| Batch_size | 16 | 16 |
| 迭代次数 | 200 | 200 |
"
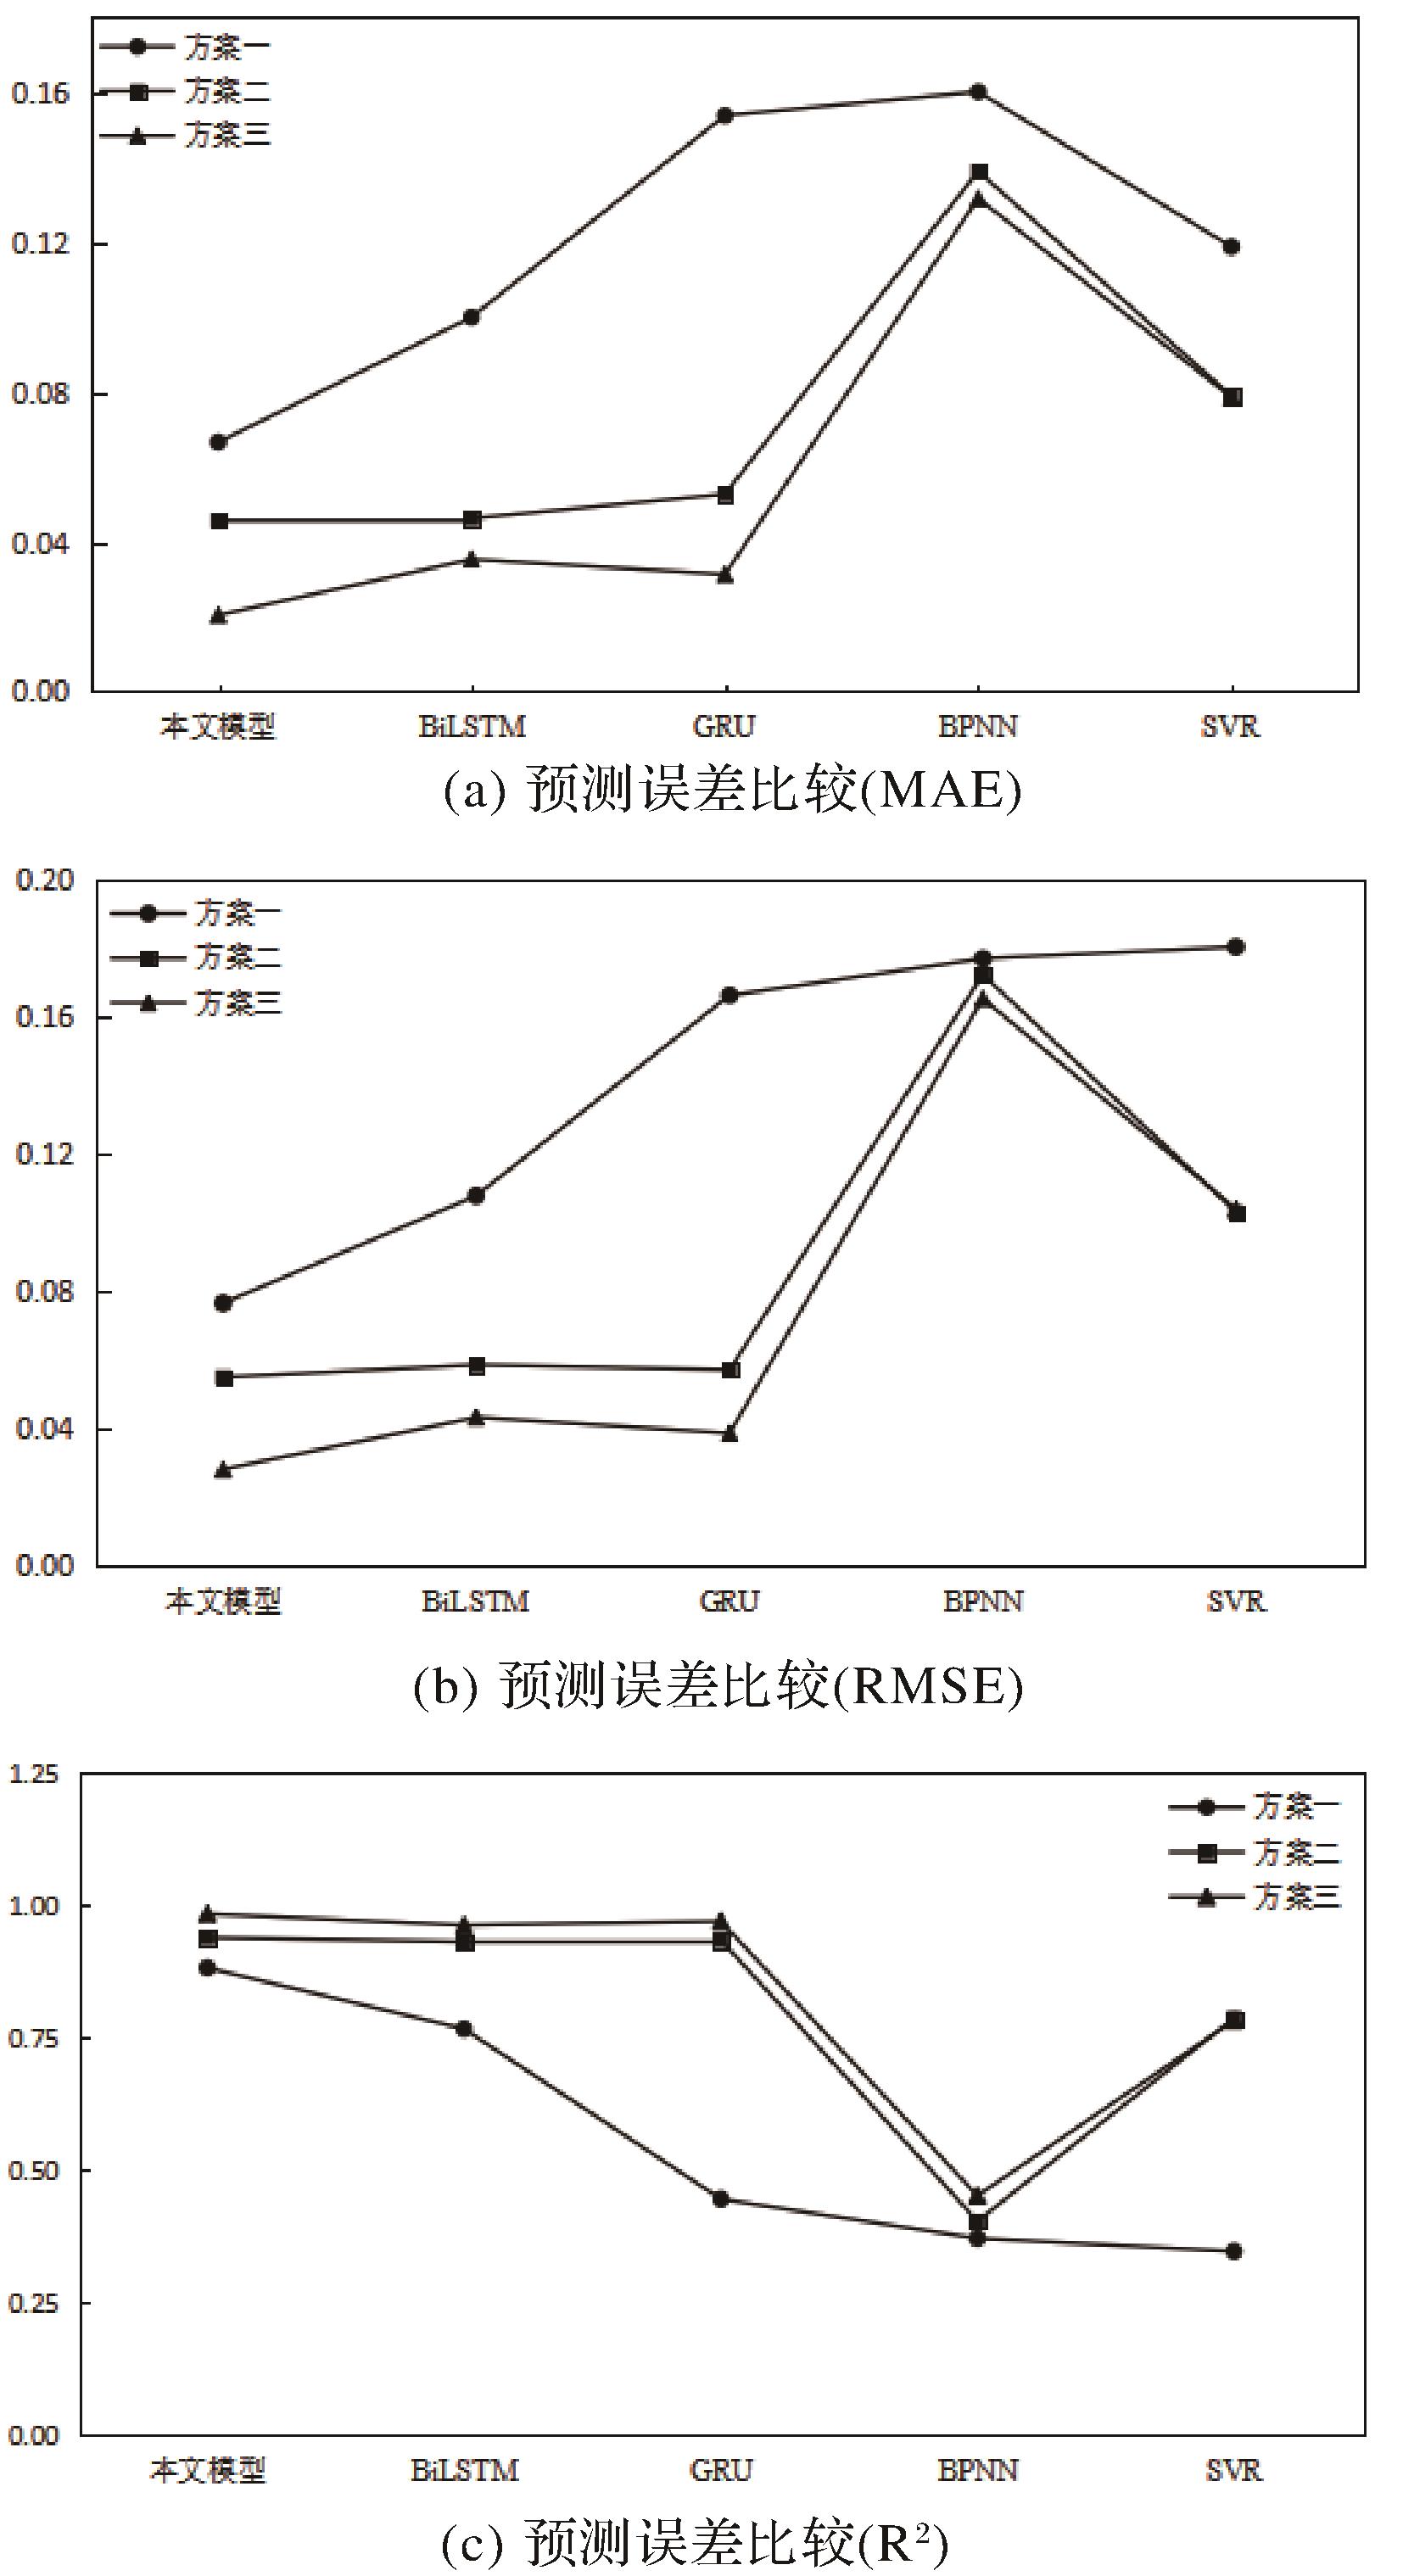
| 模型输入 | 模型 | MAE | RMSE | R2 |
|---|---|---|---|---|
| 方案一 | SVR | 0.1187 | 0.1803 | 0.3472 |
| BPNN | 0.1601 | 0.1769 | 0.3717 | |
| GRU | 0.1538 | 0.1662 | 0.4457 | |
| BiLSTM | 0.1000 | 0.1078 | 0.7669 | |
| 本文模型 | 0.0666 | 0.0764 | 0.8822 | |
| 方案二 | SVR | 0.0790 | 0.1029 | 0.7873 |
| BPNN | 0.1389 | 0.1723 | 0.4043 | |
| GRU | 0.0528 | 0.0570 | 0.9347 | |
| BiLSTM | 0.0462 | 0.0584 | 0.9314 | |
| 本文模型 | 0.0457 | 0.0548 | 0.9394 | |
| 方案三 | SVR | 0.0786 | 0.1038 | 0.7835 |
| BPNN | 0.1317 | 0.1652 | 0.4519 | |
| GRU | 0.0314 | 0.0386 | 0.9702 | |
| BiLSTM | 0.0354 | 0.0432 | 0.9626 | |
| 本文模型 | 0.0205 | 0.0280 | 0.9842 |
"
"
"
"
| 本文模型 | 对比模型 | |||
|---|---|---|---|---|
| BiLSTM | GRU | BPNN | SVR | |
| proposed | -11.5324*** | -5.9768*** | -19.6933*** | -16.3849*** |
| [1] | 刘慕涵, 熊熊. 股指期货交易政策、投资者行为与市场质量[J]. 中国管理科学, 2023,31(7): 126-139. |
| Liu M H, Xiong X. Stock index futures trading policy, investors’Behavior and stock market quality[J]. Chinese Journal of Management Science,2023,31(7): 126-139. | |
| [2] | 赵萌, 吴迟. 金融危机对中国农产品期货市场的冲击——基于事件研究法的价格敏感性测试[J]. 农业技术经济, 2010(7): 4-12. |
| Zhao M, Wu C. The impact of financial crisis on China’s agricultural futures market: Price sensitivity test based on event study[J]. Journal of Agrotechnical Economics, 2010(7): 4-12. | |
| [3] | Chu P K, Hoff K, Molnár P, et al. Crude oil: Does the futures price predict the spot price?[J]. Research in International Business and Finance, 2022, 60: 101611. |
| [4] | Adämmer P, Bohl M T. Price discovery dynamics in European agricultural markets[J]. Journal of Futures Markets, 2018, 38(5): 549-562. |
| [5] | 宋波, 邢天才. 基于价格发现和统计套期保值的铜期货波动溢出效应检验[J].统计与决策,2020,36(12): 148-151. |
| Song B, Xing T C. Tiancai.Testing the spillover effect of copper futures volatility based on price discovery and statistical hedging [J]. Statistics and Decision, 2020, 36(12): 148-151. | |
| [6] | Kertlly de Medeiros R, da Nóbrega Besarria C, Pitta de Jesus D, et al. Forecasting oil prices: New approaches[J]. Energy, 2022, 238: 121968. |
| [7] | Zhang W, Gong X, Wang C, et al. Predicting stock market volatility based on textual sentiment: A nonlinear analysis[J]. Journal of Forecasting, 2021, 40(8): 1479-1500. |
| [8] | 耿立校, 刘丽莎, 李恒昱. 多源异构数据融合驱动的股票指数预测研究[J]. 计算机工程与应用, 2021, 57(20): 142-149. |
| Geng L X, Liu L S, Li H Y. Research on stock index prediction driven by multi-source heterogeneous data fusion[J]. Computer Engineering and Applications, 2021, 57(20): 142-149. | |
| [9] | 尹海员, 寇文娟. 基于朴素贝叶斯法的投资者情绪度量及其对股票特质风险的影响[J]. 中国管理科学, 2024, 32(4): 38-47. |
| Yin H Y, Kou W J. Investor sentiment based on naive Bayes method and its impact on stock idiosyncratic risk[J]. Chinese Journal of Management Science, 2024, 32(4): 38-47. | |
| [10] | Hochreiter S, Schmidhuber J. Long short-term memory[J]. Neural Computation, 1997, 9(8): 1735-1780. |
| [11] | 欧阳红兵, 黄亢, 闫洪举. 基于LSTM神经网络的金融时间序列预测[J].中国管理科学,2020,28(4): 27-35. |
| Ouyang H B, Huang K, Yan H J. Prediction of financial time series based on LSTM neural network[J]. Chinese Journal of Management Science, 2020, 28(4): 27-35. | |
| [12] | Siami-Namini S, Tavakoli N, Namin A S. The performance of LSTM and BiLSTM in forecasting time series[C]//Proceedings of the 2019 IEEE International Conference on Big Data (Big Data),Los Angeles, CA, USA,December 9-12, IEEE, 2019: 3285-3292. |
| [13] | 陈可心, 黄刚. CStock: 一种结合新闻与股价的股票走势预测模型[J]. 计算机技术与发展, 2020, 30(9): 18-22. |
| Chen K X, Huang G. Cstock: A stock trend forecasting model combining news and stock price[J]. Computer Technology and Development, 2020, 30(9): 18-22. | |
| [14] | Li J, Li G, Liu M, et al. A novel text-based framework for forecasting agricultural futures using massive online news headlines[J]. International Journal of Forecasting, 2022, 38(1): 35-50. |
| [15] | Li Y, Jiang S, Li X, et al. The role of news sentiment in oil futures returns and volatility forecasting: Data-decomposition based deep learning approach[J]. Energy Economics, 2021, 95: 105140. |
| [16] | Bai Y, Li X, Yu H, et al. Crude oil price forecasting incorporating news text[J]. International Journal of Forecasting, 2022, 38(1): 367-383. |
| [17] | 余传明, 龚雨田, 王峰, 等.基于文本价格融合模型的股票趋势预测[J].数据分析与知识发现,2018, 2(12): 33-42. |
| Yu C M, Gong Y T, Wang F, et al. Predicting stock prices with text and price combined model[J].Data Analysis and Knowledge Discovery,2018,2(12): 33-42. | |
| [18] | 徐月梅, 王子厚, 吴子歆. 一种基于CNN-BiLSTM多特征融合的股票走势预测模型[J]. 数据分析与知识发现, 2021, 5(7): 126-137. |
| Xu Y M, Wang Z H, Wu Z X. Predicting stock trends with CNN-BiLSTM based multi-feature integration model[J]. Data Analysis and Knowledge Discovery, 2021, 5(7): 126-137. | |
| [19] | Kim Y. Convolutional neural networks for sentence classification[C]//Proceedings of the 2014 Conference on Empirical Methods in Natural Language Processing (EMNLP),Doha,Qatar, October 25-29 ,ACL, 2014: 1746-1751. |
| [20] | 张冬, 魏俊斌. 情感驱动下主流媒体疫情信息数据分析与话语引导策略[J].图书情报工作, 2021, 65(14): 101-108. |
| Zhang D, Wei J B. Emotion-driven data analysis of mainstream media epidemic information and discourse guidance strategies[J]. Library and Information Service, 2021, 65(14): 101-108. | |
| [21] | 师荣蓉, 张教萌. 中国经济高质量发展的社会评价: 基于微博情感分析的视角[J]. 统计与决策, 2021, 37(24): 180-184. |
| Shi R R, Zhang J M. Social evaluation of high-quality economic development in China: From the perspective of weibo’s emotional analysis[J]. Statistics & Decision, 2021, 37(24): 180-184. | |
| [22] | 王会娟, 陈红佳, 高思琴, 等. 基于TEI@I方法论的玉米期货价格预测研究[J]. 管理评论, 2020, 32(7): 293-301. |
| Wang H J, Chen H J, Gao S Q, et al. Forecasting corn futures prices based on TEI@I methodology[J]. Management Review, 2020, 32(7): 293-301. | |
| [23] | Wang J, Wang Z, Li X, et al. Artificial bee colony-based combination approach to forecasting agricultural commodity prices[J]. International Journal of Forecasting, 2022, 38(1): 21-34. |
| [24] | Zhang J, Meng Y, Wei J, et al. A novel hybrid deep learning model for sugar price forecasting based on time series decomposition[J]. Mathematical Problems in Engineering, 2021, 2021: 6507688. |
| [25] | Zhu Q, Zhang F, Liu S, et al. A hybrid VMD-BiGRU model for rubber futures time series forecasting[J]. Applied Soft Computing, 2019, 84: 105739. |
| [26] | 党建武, 从筱卿. 基于CNN和GRU的混合股指预测模型研究[J].计算机工程与应用,2021,57(16): 167-174. |
| Dang J W, Cong X Q. Research on hybrid stock index forecasting model based on CNN and GRU[J]. Computer Engineering and Applications, 2021, 57(16): 167-174. | |
| [27] | 陈标金, 谭莹. 信息、交易者情绪与中国农产品期货价格波动[J]. 金融经济学研究, 2017, 32(2): 66-75. |
| Chen B J, Tan Y. Information, trader sentiment and agricultural commodity futures price volatility in China[J]. Financial Economics Research, 2017, 32(2): 66-75. | |
| [28] | 白宗航. 不同流动性水平下投资者情绪对农产品期货价格波动影响研究——基于面板门槛模型的分析[J]. 价格理论与实践, 2019(6): 116-119. |
| Bai Z H. The research on investor sentiment and the volatility of agricultural futures price under different liquidity levels: Based on the panel threshold model[J]. Price (Theory & Practice), 2019(6): 116-119. | |
| [29] | Li J, Li G, Liu M, et al. A novel text-based framework for forecasting agricultural futures using massive online news headlines[J]. International Journal of Forecasting, 2022, 38(1): 35-50. |
| [30] | Li Y, Jiang S, Li X, et al. The role of news sentiment in oil futures returns and volatility forecasting: Data-decomposition based deep learning approach[J]. Energy Economics, 2021, 95: 105140. |
| [31] | 徐维军, 付志能, 李茂昌, 等. 基于新闻文本挖掘的股指期货高频预测研究[J]. 系统科学与数学, 2021, 41(7): 1856-1875. |
| Xu W J, Fu Z N, Li M C, et al. High-frequency forecasting of stock index futures based on news text mining[J]. Journal of Systems Science and Mathematical Sciences, 2021, 41(7): 1856-1875. | |
| [32] | Diebold F X, Mariano R S. Comparing predictive accuracy[J]. Journal of Business & Economic Statistics, 1995, 13(3): 253-263. |
| [1] | Zhiqiang Ye, Mengyao Lv, Shunming Zhang, Yan Zhao. Online Media Coverage and Analysts' Earnings Forecast: Based on the Limited Attention Perspective [J]. Chinese Journal of Management Science, 2026, 34(7): 117-126. |
| [2] | Jinqing Zhang, Suoer Xu. Efficient Portfolios Based on Mean-Variance Shrinkage Estimation under Mixed Normal [J]. Chinese Journal of Management Science, 2026, 34(7): 12-21. |
| [3] | Haichuan Xu, Hanliang Wang, Weixing Zhou. Measuring Financial Crises: Linking Macroeconomic Price Pressures and Microeconomic Financial Institution Capital Shortfalls [J]. Chinese Journal of Management Science, 2026, 34(5): 44-56. |
| [4] | Pu Wang, Kunpeng Li, Li Su. Can Dimensionality Reduction Enhance Deep Neural Networks in Learning Credit Risk? ——A Study Based on Factor-Augmented Explainable Learning Models [J]. Chinese Journal of Management Science, 2026, 34(5): 57-71. |
| [5] | Zhengyang Song, Zhongbao Zhou, Lean Yu, Tiantian Ren. Portfolio Optimization Strategy with a Hybrid Ensemble Forecasting Algorithm and Black-Litterman Model [J]. Chinese Journal of Management Science, 2026, 34(5): 72-85. |
| [6] | Zezhou Wang, Qifa Xu, Cuixia Jiang. Can Interaction and Dissemination of Mixed-Frequency Information in Companies' Multi-Layer Relationship Networks Improve Asset Pricing? Asset Pricing Study Based on Graph Neural Networks [J]. Chinese Journal of Management Science, 2026, 34(4): 47-62. |
| [7] | Jixian Meng, Jijia Kang, Qianqian Yang, Xiaoguang Yang. The Impact of Power Rationing Events in 2021 on China's Stock Market [J]. Chinese Journal of Management Science, 2026, 34(3): 25-38. |
| [8] | Pengqi Liu, Ping Lv. "Winner Picking" or "Winner Avoiding"? Selection Mechanism for Outward Foreign Direct Investment by China's Business Group Affiliates [J]. Chinese Journal of Management Science, 2026, 34(1): 353-368. |
| [9] | Zhaorong Huang, Zhengyang Song, Bo Yang, Nengmin Zeng, Le’an Yu. Hybrid Multivariate Regression Forecasting for Gold Prices: A Decomposition-Reconstruction-Ensemble Methodology [J]. Chinese Journal of Management Science, 2025, 33(12): 41-56. |
| [10] | Chao Liu, Lantao Xu. Study on Optimal Portfolio Strategy from the Perspective of Multilayer Temporal Network [J]. Chinese Journal of Management Science, 2025, 33(9): 46-56. |
| [11] | Jianxin Zhu, Kexin Liu, Nengmin Zeng, Xiong Wu. Competitive Network and Financial Performance: Empirical Evidence Based on Explainable Random Forest [J]. Chinese Journal of Management Science, 2025, 33(8): 75-89. |
| [12] | Longbing Xu, Wenbin Wu. Over-reaction, Jump Return and A-share Momentum Strategy [J]. Chinese Journal of Management Science, 2025, 33(6): 1-13. |
| [13] | Weiqi Liu, Jianying Li, Jie Zhou, Dongliang Yuan. Digital Transformation and Firm Value: Theory and Empirical Evidence [J]. Chinese Journal of Management Science, 2025, 33(5): 138-149. |
| [14] | Xia Liu, Yunyue Zhang, Mengqi Li, Yejun Xu. Quantum Supervised Game Model and Simulation Analysis for Manipulative Behavior in Trading Stock Market [J]. Chinese Journal of Management Science, 2025, 33(3): 24-33. |
| [15] | Jiaxian Shen, Haozhi Chen, Weiguo Zhang. Research on Systemic Risk Measurement of China’ s Foreign Exchange Market Based on Knowledge Graph Network Characteristics [J]. Chinese Journal of Management Science, 2025, 33(3): 45-61. |
| Viewed | ||||||
|
Full text |
|
|||||
|
Abstract |
|
|||||
|
||
